
How to Handle an Overdue Water Bill Before Shutoff
Learn how to handle an overdue water bill before shutoff with practical steps: negotiate a payment plan, find assistance, and compare short-term loan options.
By Grace Shaw
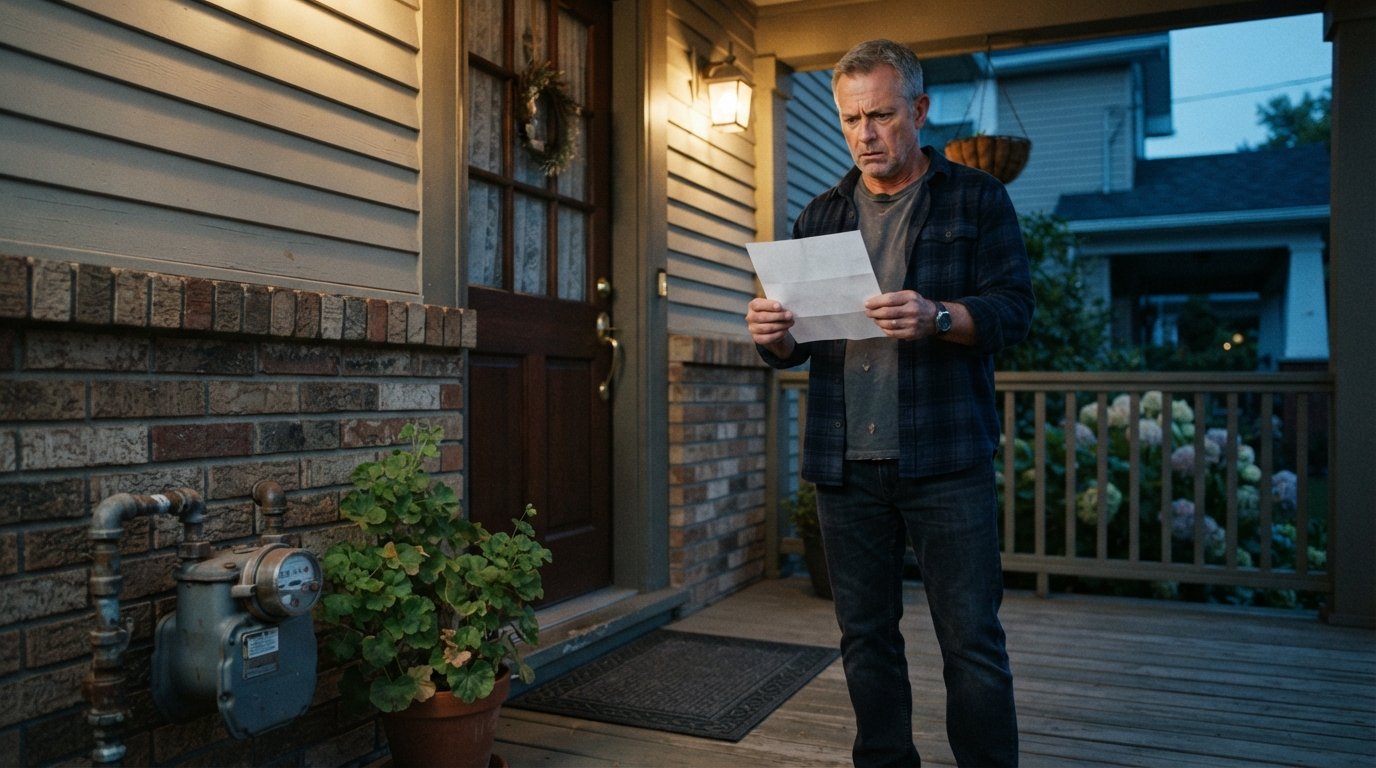
The shutoff notice is taped to your door, and the due date is looming. Your water is about to be disconnected, and you need a plan that works fast. This guide walks you through the practical steps to handle an overdue water bill before shutoff, from understanding your rights and timelines to negotiating a payment plan and finding short-term financial help if needed. You will learn how to buy yourself time, reduce the amount you owe, and avoid the costly cycle of disconnection and reconnection. Whether you are a few days late or facing a final notice, the actions you take now can keep the water flowing.
Understand the Shutoff Timeline and Your Rights
Water utilities follow a legal process before disconnection, and knowing that sequence gives you leverage. Most companies must send at least one written notice, often 10 to 30 days before a scheduled shutoff, and many provide a second or final notice with a specific date. The notice should include the amount owed, the disconnection date, and information about assistance programs or payment arrangements. If you have not received a written notice, call the utility immediately: disconnection without proper notice may violate local regulations.
Grace periods vary by state and municipality. Some utilities offer a 5 to 10 day grace period after the due date before late fees apply, while others move straight to a shutoff notice. In many jurisdictions, water cannot be shut off for certain vulnerable households, such as those with elderly residents, young children, or individuals with serious medical conditions, provided they submit documentation. Federal and state moratoriums may also be in effect during extreme weather or public health emergencies. Check your utility's website or call their customer service to confirm the exact rules for your area.
Timing is critical. If you have received a shutoff notice, do not wait. The earlier you act, the more options you have: you can request an extension, negotiate a payment plan, or apply for assistance before the final deadline. Once the shutoff order is executed, reconnection typically requires full payment plus a reconnection fee, which can range from $50 to over $200 depending on your location. Avoiding that outcome is the goal.
Contact Your Water Utility Immediately
The first and most important step is to call your water provider. Many utilities are willing to work with customers who communicate proactively. Explain your situation honestly and ask about the following options:
- Payment extensions: Some utilities grant a short extension (a few days to a few weeks) to pay the overdue amount without penalty.
- Payment plans: You may be able to split the past-due balance into installments over several months, often with a small down payment.
- Hardship programs: Many utilities have internal assistance funds or partner with local agencies to help low-income customers.
- Late fee waivers: If you have a good payment history, ask if late fees can be waived as a one-time courtesy.
When you call, have your account number, the shutoff notice, and a clear picture of your monthly budget ready. Be polite but persistent. If the first representative cannot help, ask to speak with a supervisor or the customer assistance department. Some utilities also offer online chat or email options, but a phone call is often faster for urgent matters.
If you cannot reach a resolution by phone, visit a local customer service office in person. Face-to-face communication can sometimes yield better results, especially if you bring documentation of your financial hardship, such as a recent pay stub, unemployment letter, or medical bill. The goal is to demonstrate that you are willing to pay but need temporary relief.
Explore Assistance Programs and Community Resources
Beyond the utility's own programs, numerous organizations provide help with water bills. The Low Income Home Energy Assistance Program (LIHEAP) primarily covers heating and cooling costs, but some states use LIHEAP funds for water bills as well. Check with your state's LIHEAP office to see if water assistance is included. Additionally, the Temporary Assistance for Needy Families (TANF) program and local community action agencies may offer emergency utility assistance.
Nonprofit organizations such as the Salvation Army, Catholic Charities, and local food banks often have funds designated for utility bills. Many cities have a Community Action Agency that administers federal and state grants for low-income households. These programs typically require proof of income, identification, and the shutoff notice. Apply as soon as possible, as funds are limited and may be distributed on a first-come, first-served basis.
If you are a renter, your landlord may be responsible for the water bill in some situations. Review your lease agreement. If the bill is in the landlord's name, contact them immediately to resolve the issue. If the bill is in your name but the lease includes water, you may still be responsible for paying the utility directly, so clarify the arrangement.
For those who need immediate cash to pay the bill, a small short-term loan can bridge the gap. In our guide on handling a car insurance deductible due now, we explain how to prioritize urgent bills and find fast funding, and the same principles apply to water shutoff emergencies. The key is to compare options and understand the total cost before committing.
Negotiate a Payment Plan That Works for You
If you cannot pay the full overdue amount, propose a payment plan. Most utilities prefer a plan over disconnection because it ensures they recover some money and avoid administrative costs. When negotiating, be realistic about what you can afford. A typical plan might require a down payment of 25 to 50 percent of the past-due balance, with the remainder spread over 3 to 6 months. Some utilities offer longer plans for larger debts.
Before agreeing to a plan, ask about any fees, interest, or conditions. Get the agreement in writing (or at least via email confirmation) to avoid misunderstandings. Make sure you understand the consequences of missing a payment: some plans revert to immediate shutoff if you default. Set up automatic payments or reminders to stay on track.
If your financial situation is dire, ask about a deferred payment agreement or a medical hardship extension. Some utilities will postpone disconnection for a specified period if you provide a doctor's note or proof of a qualifying life event (such as a job loss or hospitalization). These options are not always advertised, so you must ask.
Consider a Short-Term Loan to Cover the Bill
When assistance programs and payment plans are not enough, a small short-term loan can provide the cash needed to pay the overdue water bill and avoid shutoff. Options include payday loans, installment loans, and personal loans from online lenders. These loans are typically $100 to $1,000 and can be funded as soon as the next business day. However, they come with high interest rates and fees, so you must weigh the cost against the reconnection fees and inconvenience of losing water service.
Before applying, calculate the total cost of the loan: the finance charge, any origination fees, and the repayment schedule. Compare that to the reconnection fee (which can be $50 to $200) plus the possibility of a security deposit and the hassle of restoring service. In many cases, a short-term loan is cheaper than the long-term consequences of a shutoff, especially if you have a family and cannot go without water for days.
If you decide a loan is the right move, use a connection service like StartCashLoan to compare offers from multiple lenders with a single request. StartCashLoan is not a lender and does not make credit decisions, but it can connect you with third-party lenders who may offer the funds you need. Remember to borrow only what you can repay, and have a plan to pay it back on time to avoid additional fees.
When comparing loan offers, look beyond the interest rate to the annual percentage rate (APR), which includes all fees. A payday loan might have a fee of $15 per $100 borrowed, which translates to an APR of nearly 400 percent if rolled over. Installment loans may have lower APRs but longer terms. Choose the option with the lowest total cost and a repayment schedule that fits your budget.
Build a Plan to Avoid Future Arrears
Once the immediate crisis is resolved, take steps to prevent it from happening again. Start by creating a realistic monthly budget that includes your water bill as a non-negotiable expense. If your income is irregular, set aside a small amount each week for utilities. Many utilities offer budget billing, which averages your annual water usage into equal monthly payments, making it easier to plan.
Consider enrolling in autopay or paperless billing with reminders. Autopay ensures you never miss a due date, but you must have enough money in your account. If you prefer manual payments, set a calendar reminder a few days before the due date. Build a small emergency fund, even if it is just $10 or $20 per week, to cover unexpected bills.
If you are struggling with chronic financial instability, seek help from a nonprofit credit counseling agency. They can help you create a debt management plan, negotiate with creditors, and improve your financial literacy. Many agencies offer free or low-cost services. Addressing the root cause of your overdue bills, such as insufficient income or overspending, is the key to long-term stability.
Finally, stay informed about assistance programs in your area. Sign up for alerts from your utility and local social services. During economic downturns or extreme weather, additional funds may become available. By staying proactive, you can protect your water service and your peace of mind.
Handling an overdue water bill before shutoff requires quick action and a clear strategy. By understanding your rights, communicating with your utility, tapping into assistance programs, and carefully considering short-term funding options, you can keep the water running and avoid the high costs of reconnection. Take the first step today: call your utility and start the conversation.