
Car Insurance Deductible Due Now? 6 Steps to Handle It
Facing a car insurance deductible due now? Learn how to negotiate with the shop, compare small loans, and avoid payday rollover while protecting your credit.
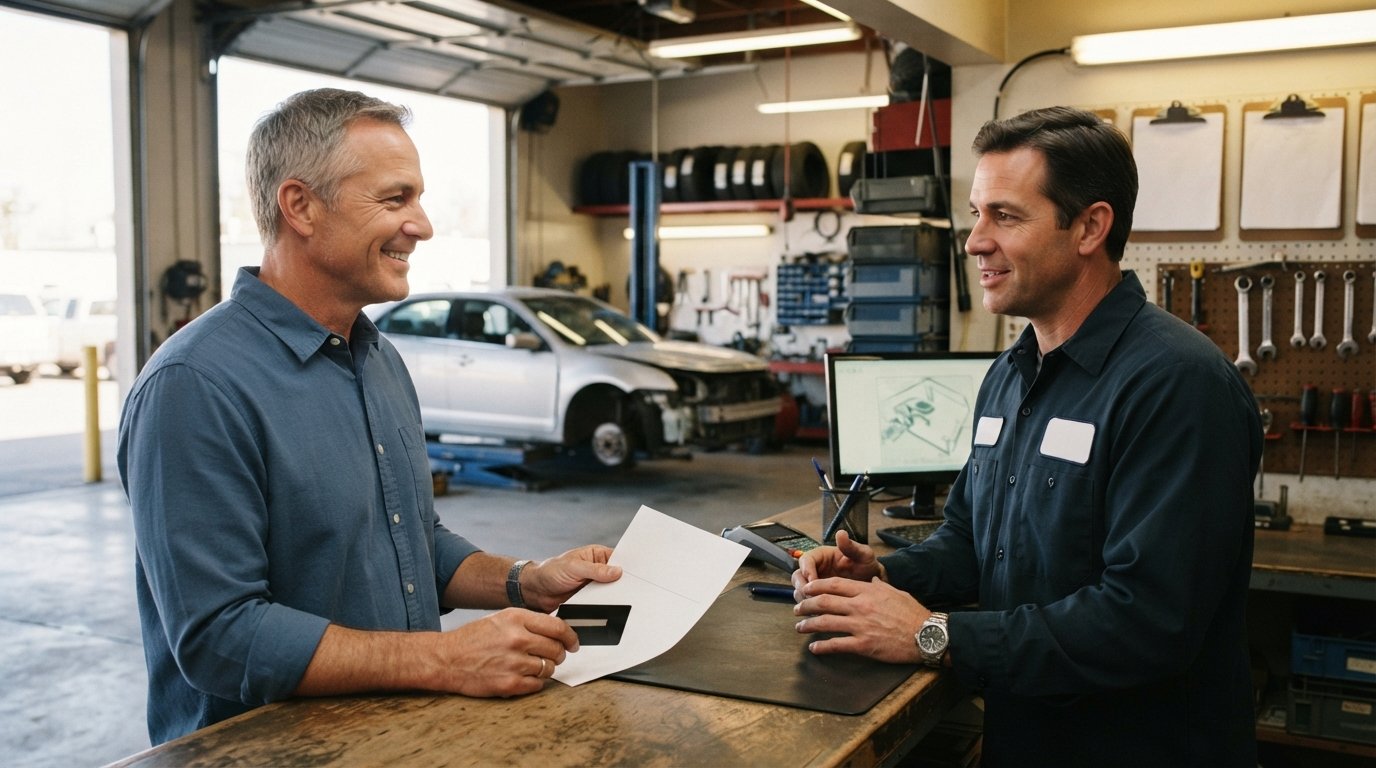
Your mechanic just called with the estimate, and the number on the invoice includes a line item you were not planning for: your deductible. The repair is approved, the part is on order, and the body shop wants the money before they release the car. If your car insurance deductible is due now and your checking account does not agree, you are not alone. Millions of drivers face this exact squeeze every year, and the good news is that you have more options than a single panicked swipe of a credit card. What matters is choosing the one that solves today's problem without creating a bigger one next month. Here is a practical playbook for what to do when your car insurance deductible is due now, from negotiating with the shop to borrowing only what you truly need.
First, Confirm What You Actually Owe and When
Before you make a single call or fill out a single form, get the numbers straight. A deductible is the amount you agree to pay out of pocket before your insurer covers the rest of a covered claim. If your policy carries a $500 deductible and the repair estimate is $2,400, your insurer pays $1,900 (minus any depreciation or limits in your policy) and you are responsible for the first $500. That part is simple. What trips people up is the timing: some shops collect the deductible when you pick up the car, some collect it when the repair is authorized, and some bill you later. Ask the shop exactly when payment is due and whether any portion can wait.
You should also verify the claim details with your insurer before you pay anything. Confirm that the adjuster has approved the estimate, that the shop is in network (if your policy has a network requirement), and that no second deductible applies. Some policies have separate deductibles for collision and comprehensive coverage, and a single incident could theoretically touch both. A five minute call to your claims representative prevents the unpleasant surprise of paying a deductible twice. If your car insurance deductible is due now because the shop is holding your vehicle, ask whether the insurer has already issued payment to the shop; sometimes the only holdup is paperwork, not money.
Talk to the Repair Shop Before You Borrow
The single most underused move in this situation is a calm conversation with the body shop or mechanic. Repair facilities deal with insurance claims every day, and many have flexible policies they will not volunteer unless you ask. Before you take out any loan, ask about three things: a payment plan, phased repairs, and deductible billing.
- Payment plans: Many independent shops will split the deductible into two or three installments over a few weeks, especially for repeat customers or larger jobs.
- Phased repairs: If part of the damage is cosmetic or non-urgent, the shop may complete the safety-critical work now and schedule the rest for when you have more cash.
- Direct billing: Some shops will bill you for the deductible after the insurer pays them, giving you a short window to gather funds without delaying the repair.
Get any arrangement in writing, even if it is just an email confirming the schedule. A handshake agreement is better than nothing, but documentation protects you if the shop changes managers or the invoice gets processed differently than promised. If the shop refuses any flexibility, ask whether they offer a third-party payment plan through a financing partner; many chains do, and those plans are often cheaper than a payday loan. Only after you have exhausted the shop's options should you start shopping for borrowed money.
Review Your Policy for Ways to Lower the Out-of-Pocket Hit
Your deductible is not always a fixed, immovable number. Read your policy declarations page and call your agent with specific questions. In some cases, you may be able to reduce what you owe today, even after a claim has been filed. A few levers are worth checking.
First, ask whether your policy includes any deductible waiver or vanishing deductible feature. Some insurers reduce your deductible by a set amount for every claim-free year, and a long clean driving record may have already lowered your obligation. Second, ask whether the shop's estimate includes items your insurer might cover outside the deductible, such as towing, rental reimbursement, or glass repair, which sometimes carries a separate and lower deductible. Third, if the repair cost is only slightly above your deductible, consider whether filing the claim is even worth it; a small claim can raise your premium for years, and paying the full repair yourself might cost less over time. Run the math before you commit.
Finally, if you genuinely cannot pay the deductible, ask your insurer whether the claim can be paid directly to you rather than the shop, or whether the shop can begin work with a partial payment. Insurers will not waive a deductible, but they can sometimes adjust the payment flow so the repair is not held hostage. Document every conversation, including the name of the representative and the date, in case you need to escalate later.
Bridge the Gap With a Small Personal or Installment Loan
Once you have squeezed what you can from the shop and your policy, a short-term loan can legitimately bridge the gap. The key is borrowing the smallest amount possible for the shortest time possible, and choosing a product whose structure matches your repayment ability. A small personal loan or installment loan is usually the better fit for a deductible, because you repay it in fixed installments over a defined period rather than all at once on your next payday.
If you are exploring this route, a comparison service can save you hours of individual applications. StartCashLoan is a free online connection service that helps U.S. consumers find short-term and payday loan options by submitting one simple request form, and it also publishes plain-language guides on borrowing and budgeting. Whether you use that service or another, compare at least three offers before signing. If you are also carrying high-interest credit card balances, our guide on how to consolidate credit card debt with a personal loan explains how to evaluate whether consolidating is cheaper than keeping multiple balances, a useful sanity check before you add new debt for a car repair.
When you compare offers, focus on the total cost of credit, not the monthly payment. A $600 loan repaid over six months at a 36 percent APR costs roughly $55 in interest, which is manageable. The same $600 borrowed as a two-week payday loan at a $15 per $100 fee costs $90 for just fourteen days, and if you roll it over even once, the cost climbs past what a personal loan would charge for the entire repayment period. The math is stark: short-duration, high-fee products are designed to be repaid quickly, and a car repair is rarely a one-paycheck problem.
Understand the Real Cost of Borrowing Small Amounts
Small loans carry a hidden trap: the fees look tiny relative to the amount borrowed, but the annualized cost can be enormous. A $20 fee on a $200 two-week loan sounds like ten percent, but annualized it is an APR above 500 percent. That is why regulators require lenders to disclose the APR, and why you should compare APRs rather than fee amounts when you shop. The monthly payment is a comfort metric; the APR is the truth metric.
Here is a simple framework for deciding whether a loan is reasonable for your deductible. First, calculate the total repayment amount (principal plus all fees and interest). Second, divide that total by your realistic monthly surplus after essential expenses. If the result is more than two or three months of tight budgeting, the loan is probably too large for your situation, and you should revisit the shop negotiation or phased repair option. Third, check whether the lender reports to credit bureaus; on-time payments on an installment loan can modestly help your credit, while a payday loan reported to a specialty bureau can hurt it if you roll over. Finally, read the prepayment terms. You want a loan with no prepayment penalty so you can pay it off early and cut the interest cost.
Also budget for the possibility that the repair costs more than the estimate. Body shops routinely find hidden damage once panels come off, and your deductible does not change, but your total out-of-pocket exposure might if the insurer disputes supplemental items. Keep a small buffer, even if it means borrowing $50 more than the deductible itself. Running out of money mid-repair is worse than paying a little interest on a slightly larger cushion.
Avoid Payday Rollover If the Due Date Beats Your Paycheck
If your deductible is due before your next paycheck and you are considering a payday loan, go in with your eyes open. Payday loans are single-payment products: the full balance comes due on your payday, typically in two to four weeks. If your paycheck is already committed to rent, groceries, and the deductible itself, you may not have the full balance available, and that is when rollover begins. Rolling over a payday loan means paying a new fee to extend the due date without reducing the principal, and each rollover adds cost without progress.
The way to avoid the rollover trap is to choose a product with installments from the start. If you must use a payday-style loan, borrow only what you can repay in full from a single paycheck after covering essentials, and never treat rollover as a plan. Better yet, ask the lender about an extended payment plan, which many states require lenders to offer at least once per year. If your state does not require it, ask anyway; some lenders will accommodate a first-time extension. And if you find yourself considering a second loan to pay off the first, stop and call a nonprofit credit counselor. That pattern is the beginning of a debt spiral, and it is far easier to break before it starts.
One more safeguard: never pay a deductible with a credit card cash advance unless you have no alternative. Cash advance APRs are typically higher than purchase APRs, interest starts accruing immediately with no grace period, and the transaction fee is often three to five percent. A small installment loan is almost always cheaper than a cash advance for the same amount.
Protect Yourself and Plan for the Next Deductible
Once the repair is done and the loan is in place, take three steps to protect yourself. First, set up automatic payments on the loan so a late fee never compounds the cost; a single missed payment can trigger penalty APRs above 30 percent on some products. Second, add your deductible amount to your emergency fund target. A common guideline is to save enough to cover your insurance deductible plus one month of essential expenses, and a dedicated sub-account labeled "car deductible" makes the goal concrete. Third, revisit your policy at renewal. Raising your deductible lowers your premium, but only choose a deductible you could actually pay in cash; the cheapest policy is the one you can afford to use.
If the repair left you with lingering medical bills or multiple financial hits at once, prioritize the obligations that carry the highest cost of missing a payment, and communicate early with every company you owe. Lenders and shops would almost always rather arrange a plan than chase a debt. The worst outcome is silence, because silence turns a manageable deductible into a collections account. Handle the calls today, borrow deliberately if you must, and treat the whole episode as a prompt to build the cushion that makes the next deductible a nuisance instead of a crisis.