
How to Cover a Surprise Car Registration or Inspection Fee
A surprise car registration or inspection fee can derail your budget. Discover payment plans, small loan options, and smart timing tips to cover the cost without lasting debt.
By Nathan Ellis
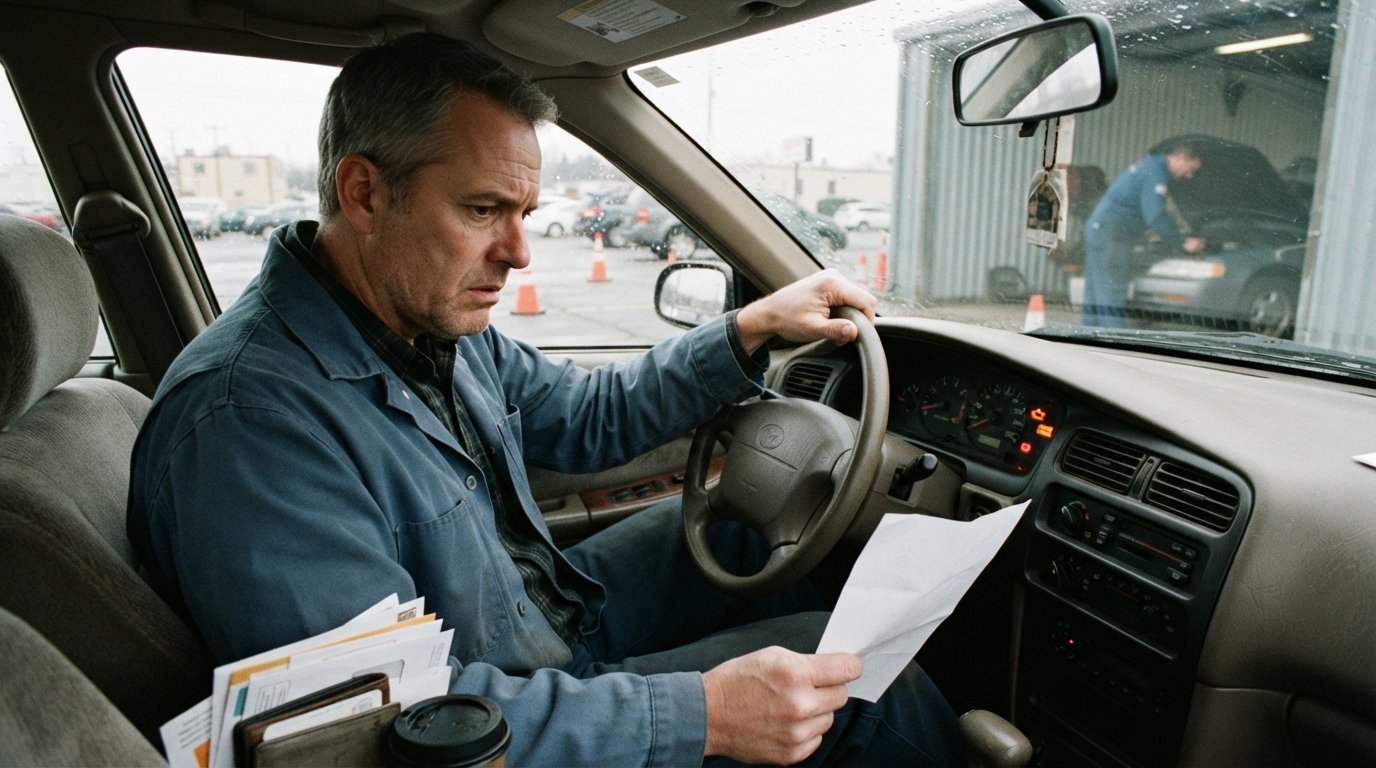
The notice arrives with little warning: your car registration is due, and the inspection sticker has expired. Suddenly you are facing a combined bill that can run into the hundreds of dollars, and the deadline is just days away. This scenario is more common than you might think, especially for drivers living paycheck to paycheck. The good news is that you have more options than simply panicking or ignoring the notice. From payment plans at your local motor vehicle agency to small short-term loans designed for urgent expenses, there are practical ways to handle a surprise car registration or inspection fee without derailing your entire budget.
Why Registration and Inspection Costs Often Arrive Together
In many states, vehicle registration renewal and safety or emissions inspections are scheduled on the same cycle. Your registration renewal notice may require proof of a valid inspection before you can complete the renewal. This means you cannot simply pay the registration fee and be done; you must also pay for the inspection itself, which can range from $20 to over $100 depending on your state and the type of inspection required. When both costs hit at once, the total can easily exceed what you have available in your checking account.
Another reason these expenses feel sudden is that they are easy to overlook. Unlike a monthly car payment, registration and inspection fees are often annual or biennial. You might forget the due date until the notice appears in your mailbox, or you might misplace the notice entirely. By the time you remember, late fees may have already started to accrue. Understanding this pattern can help you plan ahead in future years, but when you are facing the bill right now, you need immediate solutions.
Additionally, some states require an inspection before you can even renew your registration, creating a chicken-and-egg problem: you need the inspection to register, but you need the registration to legally drive to the inspection station. This logistical wrinkle adds stress and can force you to take time off work or make multiple trips, further increasing the indirect costs of compliance.
Check for Payment Plans Through Your Motor Vehicle Agency
Before you consider borrowing money, find out whether your state's motor vehicle department offers a payment plan for registration fees. Many agencies understand that vehicle owners sometimes face financial hardship and have implemented installment options. These plans allow you to split the registration fee into smaller monthly payments, often with a modest administrative fee. The application process is usually straightforward and can be completed online or at a local office.
For example, some states allow you to pay registration in two or four installments, with the first payment due at the time of renewal. Others offer a grace period during which you can pay without penalty, giving you a few extra weeks to gather the funds. It is worth visiting your state's motor vehicle website or calling the customer service line to ask about available options. Be prepared to explain your situation and ask specifically about hardship plans or installment agreements.
Keep in mind that payment plans may not cover inspection fees, which are typically paid directly to the inspection station. However, some inspection stations offer their own payment arrangements, especially if you are a repeat customer. It never hurts to ask. If you can split the total cost into smaller chunks, you reduce the immediate financial pressure and avoid the need for a loan altogether.
If you do decide to use a payment plan, make sure you understand the terms: when each payment is due, whether there are late fees, and whether the plan affects your ability to renew in the future. Missing a payment on a registration plan could result in additional penalties or even suspension of your registration, so only commit if you are confident you can meet the schedule.
Small Loan Options When the Deadline Is Tight
When the due date is just days away and a payment plan is not available or would still leave you short, a small short-term loan can bridge the gap. Online loan connection services like FundingCashLoans allow you to submit a single request and get matched with third-party lenders who may offer payday loans, installment loans, or personal loans. These loans are designed for urgent expenses and can provide funds as soon as the next business day, which is often fast enough to meet a registration deadline.
Another option is a personal loan from a bank or credit union. If you have an existing relationship with a financial institution, they may offer a small personal loan with a lower interest rate than a payday loan. Credit unions, in particular, are known for being more flexible with members who have less-than-perfect credit. However, approval can take longer than an online connection service, so this route works best if you have a few days of lead time.
For those with bad credit, finding affordable financing can be challenging. That is why it is important to compare offers from multiple lenders before committing. A service like FreeQuotes.Loans lets you submit one request form and receive quotes from a network of lending partners, which can save you time and help you find a loan with terms that fit your budget. Remember that FreeQuotes.Loans is not a lender and does not make credit decisions; all loan terms are set by the matched lenders.
When considering a short-term loan, pay close attention to the annual percentage rate (APR) and any fees. Payday loans, for example, can carry APRs of 400% or more, which means a $200 loan could cost you $30 to $60 in fees for a two-week term. If you cannot repay the loan on time, the costs can escalate quickly. Installment loans spread the cost over several months, which may be more manageable, but you will pay interest over a longer period. Always borrow only what you need and have a clear plan to repay.
Keep the Request Amount Close to the Actual Bill
One of the biggest mistakes borrowers make when facing a surprise expense is borrowing more than necessary. It is tempting to round up or add a little extra for peace of mind, but every extra dollar you borrow adds to the cost of the loan through interest and fees. Before you apply, add up the exact amount of your registration fee, inspection fee, and any late penalties. Then borrow only that amount, plus a small buffer if you anticipate additional costs like a reinspection fee.
For instance, if your registration is $150 and the inspection is $40, your total is $190. Borrowing $200 is reasonable; borrowing $500 because you might need it for something else is not. Keeping the loan amount close to the actual bill reduces your monthly payment and makes it easier to repay on time, which protects your credit score and avoids a cycle of debt.
It also helps to have a repayment plan in place before you accept a loan. Look at your next paycheck and determine how much you can realistically set aside to repay the loan. If the repayment date falls before your next payday, you may need to adjust the term or find a lender with more flexible repayment options. Some lenders allow you to choose a due date that aligns with your pay schedule, which can make repayment much easier.
Consider Timing the Expense Next Year to Avoid New Debt
Once you have handled the immediate crisis, take steps to avoid being caught off guard next year. The best way to do this is to set up a sinking fund: a dedicated savings account where you set aside a small amount each month to cover future registration and inspection costs. If you know your total annual cost is around $200, saving just $17 per month will have you covered by the time the notice arrives. This approach eliminates the need for loans and the associated interest.
You can also mark your calendar with reminders a month before the due date. Many states offer email or text reminders when your registration is due, so sign up for those notifications if available. If you tend to forget because of a busy schedule, a simple phone alert can make a big difference. Additionally, some states allow you to renew your registration up to 90 days in advance, so you can pay early and avoid the last-minute rush.
If you know that your inspection is due at the same time, consider getting the inspection done a few weeks before the registration renewal. This gives you time to address any issues that might cause a failed inspection and need for repairs, which can add unexpected costs. By spreading out the tasks, you reduce the financial and logistical burden when the deadlines converge.
Finally, review your budget regularly to identify areas where you can cut back and redirect those savings toward your vehicle compliance fund. Even small adjustments, like packing lunch instead of eating out, can free up enough money to cover these predictable expenses without borrowing. The goal is to transform a surprise into a planned event, so you never have to scramble for cash again.
If you find yourself needing a small loan to cover your car registration or inspection fee, remember to explore all your options first. Payment plans, credit union loans, and online connection services each have their pros and cons. For those with bad credit, our guide on how to cover a car repair with bad credit in 2026 offers additional strategies that can apply to any urgent vehicle expense. And if you decide to use a loan connection service, be sure to read the terms carefully and borrow only what you need to get back on the road legally and safely.