
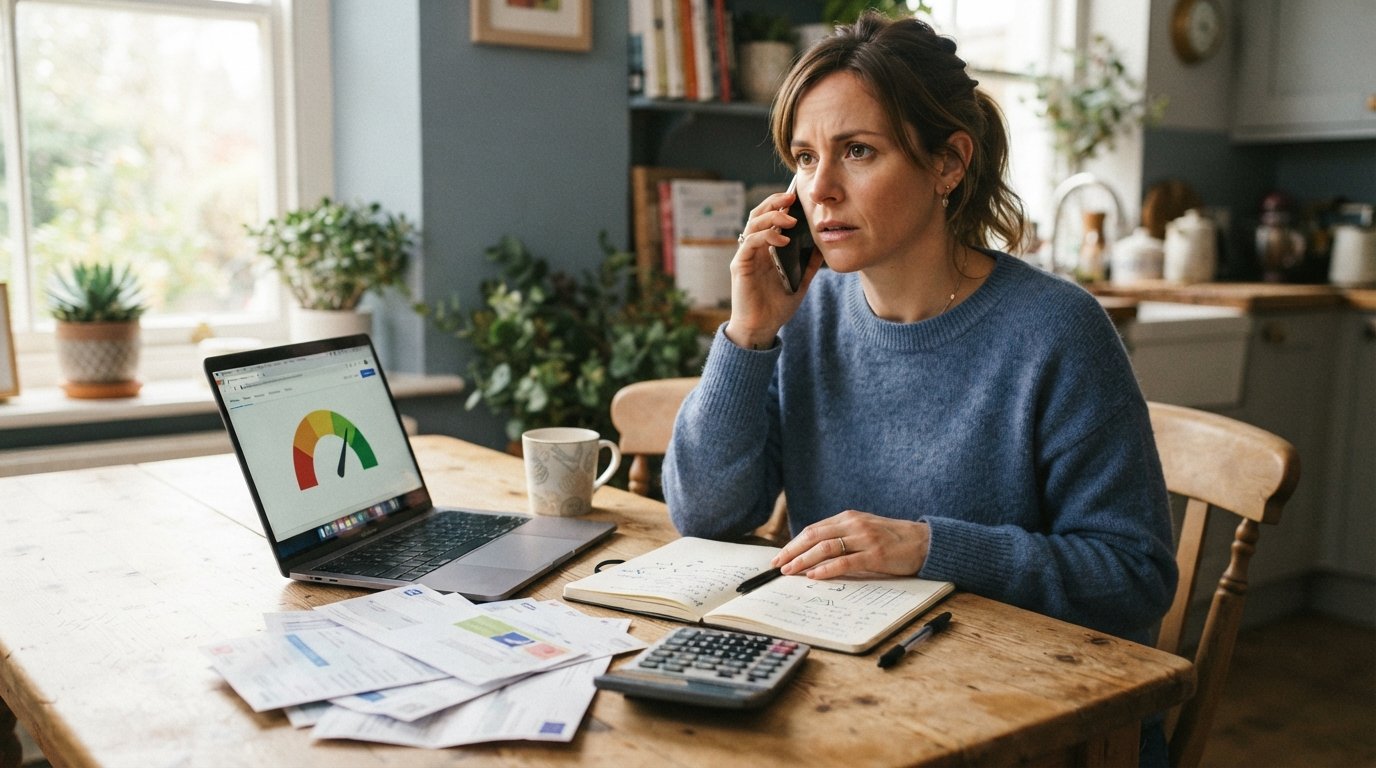
Proactive Steps to Protect Your Credit Score During Financial Hardship
Take proactive steps to protect your credit score during financial hardship. Contact creditors early, prioritize reported accounts, and build a bare-bones budget to avoid missed payments.
By Laura Carter
Your credit score can feel like a lifeline when money gets tight, and the last thing you need is to watch it sink just when you need it most. The good news is that you do not have to be a passive victim of financial hardship. By taking action before a missed payment hits your report, you can shield your score from unnecessary damage and keep your options open for the future. This guide walks you through the proactive steps to protect your credit score during financial hardship, from early conversations with creditors to building a bare-bones budget that keeps your minimum payments on track.
Why Proactive Credit Protection Matters During Financial Hardship
When financial trouble looms, it is natural to focus on immediate cash flow and put credit concerns on the back burner. But your credit score is a long-term asset that affects everything from your ability to rent an apartment to the interest rate you pay on future loans. A drop of even 50 points can cost you thousands of dollars over time in higher borrowing costs. During hardship, the actions you take in the first 30 to 60 days can determine whether your score takes a small hit or a catastrophic plunge.
Proactive steps to protect your credit score during financial hardship are not about hiding from reality. They are about making strategic decisions that minimize damage while you work through your situation. Creditors are often more willing to help than borrowers expect, but they typically reserve hardship programs for those who reach out before a payment is missed. Waiting until you are already delinquent limits your options and can trigger negative reporting that lingers for years.
Another reason to act early is that credit scoring models weigh recent activity heavily. A single missed payment can drop a good score by 100 points or more, and the impact is strongest in the first few months. By contrast, a proactive arrangement with a creditor, such as a reduced payment plan or a deferment, may not be reported as negative at all. The key is to communicate before the problem escalates and to document every agreement you make.
Contact Creditors Early and Ask About Hardship Programs
The single most effective proactive step you can take is to contact your creditors before you miss a payment. Many lenders, credit card issuers, and loan servicers have formal hardship programs designed to help borrowers who are facing temporary financial difficulty. These programs can include reduced interest rates, waived fees, extended repayment terms, or temporary payment deferments. The catch is that they are almost always easier to access before your account becomes delinquent.
When you call, be prepared to explain your situation clearly and concisely. Let the representative know that you are experiencing a temporary hardship, such as a job loss, medical emergency, or reduction in income, and that you want to keep your account in good standing. Ask specifically about hardship programs, forbearance options, or any other assistance they offer. Do not be afraid to ask for a supervisor if the first person you speak with is not helpful. Persistence often pays off.
It is equally important to get any agreement in writing. Verbal promises can be lost or misrecorded, and you need a paper trail if a negative mark appears on your report later. Ask the creditor to send you a confirmation email or letter that outlines the terms of your arrangement, including the payment amount, due dates, and how the account will be reported to the credit bureaus. Keep copies of all correspondence in a safe place.
If you are considering a loan to bridge your hardship, be careful about how you shop. Every application can trigger a hard inquiry, which may ding your score. Using a service like a loan matching service that protects your credit score can help you compare offers from multiple lenders with a single request, reducing the number of inquiries on your report. This is especially valuable when you need to act quickly but still want to protect your credit.
Prioritize Accounts Reported to Bureaus and Avoid New Applications
Not all bills affect your credit score equally. Most utility payments, rent, and cell phone bills are not reported to the major credit bureaus unless you are seriously delinquent and the account is sent to collections. By contrast, credit cards, auto loans, personal loans, and mortgages are typically reported every month. When money is tight, prioritize payments on accounts that are actively reported to the bureaus, because those are the ones that will directly impact your score.
Here is a simple framework to help you prioritize:
- First priority: Accounts that are already reported to the bureaus and are current or only slightly past due. Keeping these accounts in good standing protects the bulk of your score.
- Second priority: Accounts that are reported but already delinquent. Bringing these current can stop further damage and may even improve your score over time.
- Third priority: Non-reported accounts that are essential for daily living, such as utilities and rent, especially if nonpayment could lead to eviction or service shutoff.
- Lowest priority: Non-reported accounts that are not essential and can be negotiated or deferred without immediate consequences.
At the same time, avoid applying for new credit unless it is absolutely necessary. Each hard inquiry can lower your score by a few points, and the effect multiplies if you apply for multiple accounts in a short period. If you must apply for a loan, do your research first and use a connection service that lets you submit one request and receive multiple offers from third-party lenders. StartCashLoan is a free online connection service that helps U.S. consumers find short-term and payday loan options with a single request form, which can reduce the number of inquiries on your credit report. Remember that StartCashLoan is not a lender and does not make credit decisions; any loan terms come directly from the lender.
Monitor Your Report for Errors and Set Up Fraud Alerts
Financial hardship can make you more vulnerable to identity theft and credit reporting errors. When you are stressed and distracted, it is easy to miss a fraudulent account or a misreported late payment. That is why monitoring your credit report regularly is a critical proactive step. You are entitled to free copies of your reports from the three major bureaus (Equifax, Experian, and TransUnion) through AnnualCreditReport.com. Review each report carefully for accounts you do not recognize, incorrect balances, or late payments that should not be there.
If you spot an error, dispute it immediately with the bureau and the creditor. Under the Fair Credit Reporting Act, the bureau must investigate your dispute within 30 days and correct any inaccurate information. This process is free and can restore points that were unfairly deducted from your score. Do not assume that a small error is harmless; even a single misreported late payment can lower your score significantly.
If your personal information has been compromised, or if you simply want extra protection during a turbulent time, consider placing a fraud alert or a credit freeze on your files. A fraud alert tells creditors to verify your identity before opening new accounts, and it is free and lasts for one year. A credit freeze goes further by preventing lenders from accessing your report entirely, which makes it nearly impossible for identity thieves to open new accounts in your name. You can lift a freeze temporarily if you need to apply for credit yourself.
Build a Bare-Bones Budget That Keeps Minimum Payments on Track
When income drops or expenses spike, the first casualty is often financial organization. You may start to avoid looking at your bank account or putting off bills because you are afraid of what you will see. This avoidance is understandable, but it can lead to missed payments and late fees that damage your credit. A bare-bones budget is a simple tool that helps you stay in control without overwhelming you.
Start by listing your essential expenses: housing, utilities, food, transportation, insurance, and minimum debt payments. These are the non-negotiables. Then, identify any remaining income and allocate it first to the minimum payments on your credit accounts. Even if you can only pay the minimum, paying on time every month is far better for your score than paying nothing. Set up automatic payments or calendar reminders to ensure you never miss a due date.
If your income is not enough to cover even the minimums, you have a few options. You can contact creditors to negotiate lower payments (as discussed earlier), seek temporary assistance from community programs, or consider a small loan to bridge the gap. If you choose to borrow, be sure to compare offers carefully and understand the true cost of the loan, including fees and interest. A loan should be a last resort, not a first step, but when used wisely it can help you avoid missed payments and protect your credit.
Finally, review your budget every week, not just once a month. Financial hardship often brings rapid changes, and a weekly check-in helps you spot problems early. Celebrate small wins, such as making all minimum payments on time for a month, and adjust your plan as your situation evolves. The goal is not perfection but consistency.
Putting It All Together: A Proactive Credit Protection Plan
The proactive steps to protect your credit score during financial hardship are not complicated, but they require discipline and early action. To summarize, here is a simple action plan you can follow:
- Reach out to creditors early: Ask about hardship programs before you miss a payment, and get any agreement in writing.
- Prioritize reported accounts: Focus your limited funds on credit cards, loans, and other accounts that are reported to the bureaus.
- Avoid unnecessary credit applications: Each hard inquiry can cost you points, so use a single-request connection service if you need to shop for a loan.
- Monitor your credit reports: Check for errors and dispute inaccuracies promptly, and consider a fraud alert or credit freeze if you are at risk.
- Build a bare-bones budget: Track essential expenses and ensure minimum payments are made on time, every time.
Financial hardship is stressful, but it does not have to destroy your credit. By taking these proactive steps, you can minimize the damage and position yourself for a faster recovery when your situation improves. Remember that creditors and lenders are often willing to work with you, but they can only help if you reach out before the problem escalates. Stay organized, communicate openly, and keep your long-term financial health in mind.