
What to Do If a Loan Offer Seems Too Good to Be True
Spot a too-good-to-be-true loan offer? Learn scam tactics, verification steps, and how to report fraud to protect your money and identity.
By Marcus Owens
You open your inbox or answer a call, and someone is offering you a loan with an impossibly low interest rate, guaranteed approval, and cash in your account within minutes. It feels like a lifesaver in a tight spot, but a small voice in your head asks: is this real? That instinct is worth listening to. Loan scams are sophisticated, and they often target people who need money urgently. Knowing what to do if a loan offer seems too good to be true can protect you from losing hundreds or thousands of dollars, and from handing over sensitive personal information to criminals.
This guide walks you through the red flags, the verification steps, and the actions to take when an offer feels off. You will learn how legitimate lenders operate, why guarantees are a warning sign, and how to report suspected fraud. The goal is not to make you paranoid but to help you borrow safely and confidently, especially when you are under financial pressure.
Common Tactics Used in Loan Scams
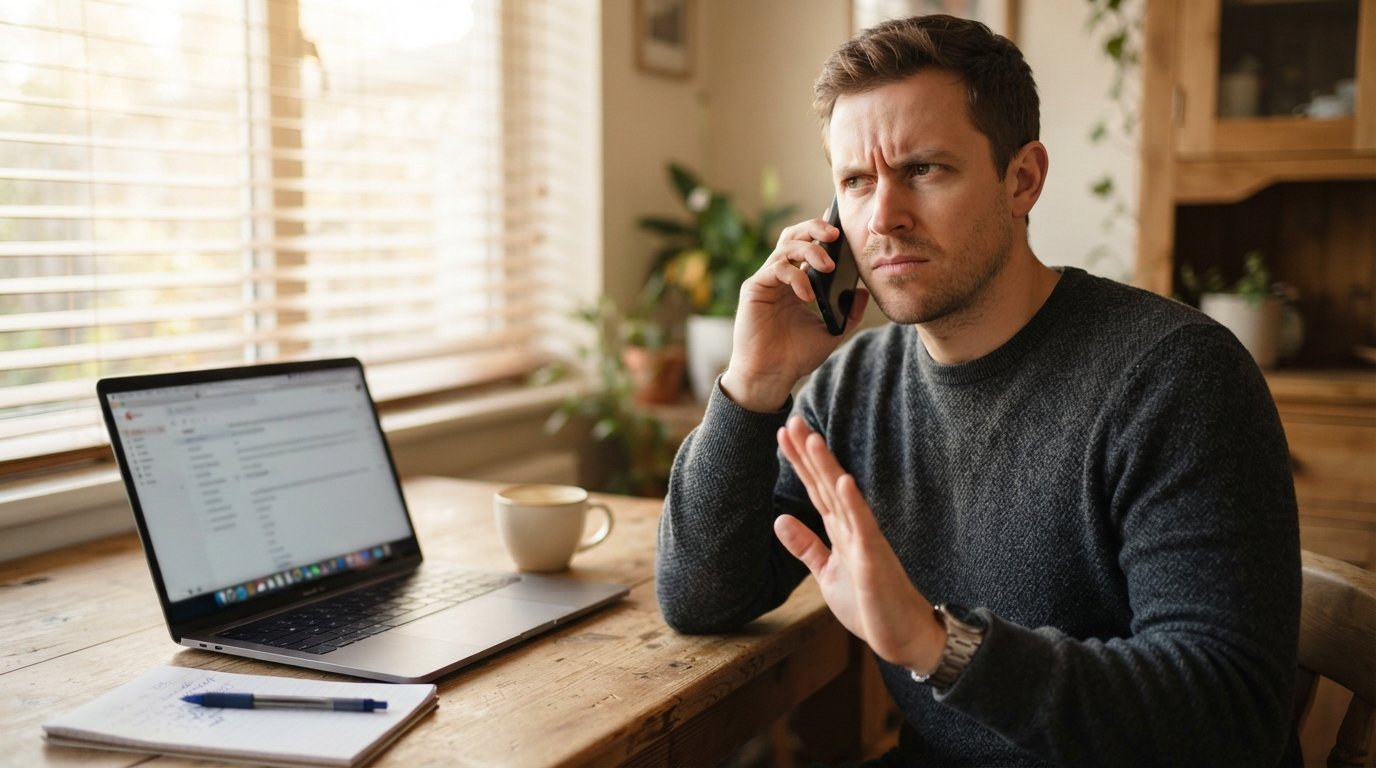
Scammers rely on urgency and emotion to override your better judgment. They know you are stressed about bills, car repairs, or medical expenses, and they exploit that stress. One of the most common tactics is the unsolicited offer: you receive a call, text, or email out of nowhere promising a loan you never applied for. Legitimate lenders generally do not cold-call or spam you with pre-approved offers unless you have an existing relationship or have opted in. If you have not submitted a request, treat the offer as suspect.
Another major red flag is pressure to act fast. Scammers will tell you the offer expires in a few hours, or that multiple people are competing for the same funds. This is designed to stop you from doing research or asking questions. Legitimate lenders may have time-sensitive rates, but they will never rush you into signing without giving you time to review the terms. If someone insists you must pay a fee upfront to secure the loan, that is almost always a scam. Real lenders deduct fees from the loan proceeds or disclose them clearly; they do not ask for gift cards, wire transfers, or cryptocurrency before you receive funds.
Scammers also ask for sensitive information too early. They may request your Social Security number, bank account login, or a copy of your ID before you have even seen a loan agreement. While legitimate lenders do need this information eventually, they collect it through secure channels after you have agreed to proceed. A legitimate lender will also provide a physical address and a license number. If the only contact method is a mobile phone or a free email service, be very cautious.
Here are five frequent scam tactics to watch for:
- Unsolicited loan offers via phone, text, or email that you did not request.
- Guaranteed approval regardless of your credit history or income.
- Requests for upfront payment (often called a processing fee, insurance fee, or collateral).
- Pressure to act immediately or risk losing the offer.
- Requests for unusual payment methods such as gift cards, wire transfers, or crypto.
Recognizing these patterns is the first step. The next step is learning how to verify whether a lender is legitimate before you share any information or money.
How to Verify a Lender Before You Commit
Verification does not have to be complicated, but it does require a few minutes of research. Start by checking whether the lender is licensed to operate in your state. In the United States, most lenders must be licensed by the state they operate in, and many states publish a database of licensed lenders. You can search your state's financial regulator website or the Nationwide Multistate Licensing System (NMLS) Consumer Access database. If the lender is not listed, that is a serious red flag. A legitimate lender will proudly display its license information and NMLS number on its website.
Next, search for complaints and reviews. Use a search engine to look up the lender's name along with terms like "scam," "complaints," or "reviews." Check the Better Business Bureau (BBB) and consumer protection sites. Keep in mind that even legitimate lenders may have some complaints, but a pattern of fraud allegations or unresolved disputes is a warning sign. Also verify the lender's contact information: does the website have a physical address and a phone number that actually works? Call the number and see if you reach a real person. Scammers often use fake addresses or virtual offices.
Finally, read the loan agreement carefully. Look for the annual percentage rate (APR), the total cost of the loan, repayment terms, and any fees. Legitimate lenders provide this information in writing before you sign. If the lender refuses to provide a written agreement or pressures you to sign without reading, walk away. You can also check if the lender is a member of a reputable industry association, such as the Online Lenders Alliance, though membership alone is not a guarantee of legitimacy.
If you are comparing multiple offers, a good practice is to use a trusted comparison service that vets lenders. For example, FreeQuotes.Loans connects borrowers with a network of third-party lenders and provides educational resources about responsible borrowing. You can learn more about their process and how they help consumers find options by visiting 4Payday. However, always do your own due diligence on any lender you are matched with.
Why Legitimate Lenders Never Guarantee Approval
No legitimate lender can guarantee approval before reviewing your application. Lending involves risk, and every lender must assess your creditworthiness, income, and ability to repay. Even if you have perfect credit, the lender still needs to verify your information and check for existing debts. A promise of guaranteed approval is a hallmark of a scam because it ignores the basic principles of lending. Scammers use this promise to lure you in, then ask for an upfront fee or steal your identity.
Legitimate lenders may advertise that you are "pre-qualified" or "pre-approved," but these terms have specific meanings. Pre-qualification is an estimate based on a soft credit check and does not guarantee final approval. Pre-approval is stronger but still conditional on verifying your income and other factors. If a lender says you are approved before you have provided any documentation, be skeptical. Also, be wary of lenders who claim they do not check credit at all. While some payday and installment lenders offer loans without traditional credit checks, they still verify income and identity, and they still assess risk. A complete absence of any verification is a red flag.
Another reason legitimate lenders avoid guarantees is regulatory compliance. State and federal laws require lenders to disclose terms and ensure borrowers can repay. A lender that guarantees approval is likely operating outside the law. If you encounter such an offer, report it to the authorities (more on that below).
How FreeQuotes.Loans Vets Lending Partners
FreeQuotes.Loans is not a direct lender; it is a connection service that matches borrowers with third-party lenders. The platform takes steps to vet the lenders in its network, though it does not guarantee loan approval or specific terms. When you submit a request, FreeQuotes.Loans shares your information with lending partners who may make you an offer. The service emphasizes transparency and security, using 256-bit SSL encryption to protect your data. It also provides educational content to help you understand loan types and responsible borrowing.
While FreeQuotes.Loans vets its partners, you should still verify any lender that contacts you. The platform encourages borrowers to review loan terms carefully and to ask questions. Because FreeQuotes.Loans does not charge fees for its connection service, any lender that asks you for an upfront fee to "secure" the loan is likely not part of a legitimate network. If you are matched with a lender that seems suspicious, you can report it to FreeQuotes.Loans and to the appropriate authorities.
Using a connection service can save time, but it does not transfer the responsibility of due diligence to the service. Always confirm the lender's license, read the agreement, and trust your instincts if something feels wrong.
Steps to Take When an Offer Feels Wrong
If you suspect a loan offer is a scam, act quickly to protect yourself. First, stop communicating with the suspected scammer. Do not provide any more personal information, and do not send money. If you have already shared bank account details, contact your bank immediately to close the account or place a freeze. If you have given your Social Security number, consider placing a fraud alert or credit freeze with the major credit bureaus (Equifax, Experian, and TransUnion).
Next, report the scam to the authorities. The Federal Trade Commission (FTC) collects complaints about fraud at ReportFraud.ftc.gov. You can also file a complaint with your state's attorney general office and the Consumer Financial Protection Bureau (CFPB). If the scam involved a website, you can report it to the Internet Crime Complaint Center (IC3). Reporting helps law enforcement track and shut down fraudulent operations, and it may help you recover losses (though recovery is not guaranteed).
Here is a step-by-step action plan:
- Stop all communication and do not send money or additional information.
- Contact your bank to secure your accounts if you shared financial details.
- Place a fraud alert or credit freeze with the credit bureaus.
- Report the scam to the FTC, your state attorney general, and the CFPB.
- Warn friends and family about the scam to prevent others from falling victim.
After reporting, monitor your credit reports and bank statements for unusual activity. Consider setting up alerts for new accounts or inquiries. Scammers may try to use your information later, so vigilance is key.
Protecting Yourself in the Future
The best defense against loan scams is knowledge and caution. Before applying for any loan, research the lender and understand the terms. Use reputable comparison services like FreeQuotes.Loans, but always verify the lender you are matched with. Never pay an upfront fee for a loan, and never share your bank login credentials. Legitimate lenders will not ask for your online banking username and password; they may ask for account numbers, but only after you have agreed to proceed.
Also, be mindful of how you share information online. Use strong, unique passwords and enable two-factor authentication on financial accounts. Check your credit report annually for free at AnnualCreditReport.com and dispute any errors. If you are in a desperate financial situation, reach out to a nonprofit credit counselor for guidance. They can help you create a budget and explore legitimate options.
Remember that if an offer seems too good to be true, it almost certainly is. Trust your gut, take your time, and verify everything. For more tips on comparing loan offers safely, see our guide on how to compare loan offers and secure the best terms. Stay informed, and do not let urgency push you into a bad decision.
By following these steps, you can protect yourself from scams and find legitimate loan options that fit your needs. Remember, responsible borrowing starts with awareness.