
What Is an Emergency Loan and When to Use One
An emergency loan covers urgent expenses fast, often within 24 hours. Learn when to use one and how to avoid the debt cycle.
By Miles Kensington
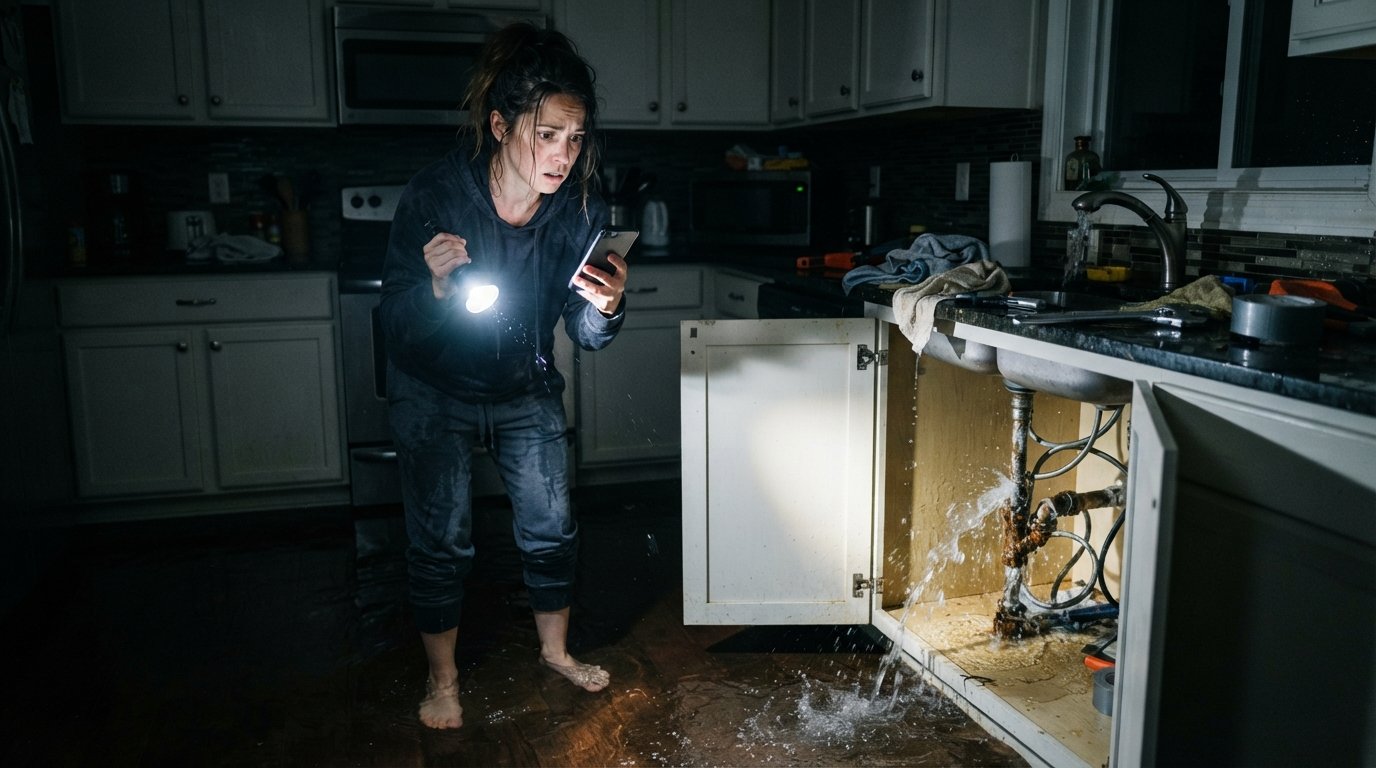
A burst pipe floods your kitchen on a Sunday night. Your car's transmission fails on the way to work. The emergency room visit you thought was covered turns out not to be. These moments share one brutal trait: they demand money you do not have right now. An emergency loan exists for exactly these situations, but it is also one of the most misunderstood financial tools available. Used wisely, it can bridge a short-term gap and protect you from far worse outcomes, like a utility shutoff, a missed mortgage payment, or a repossession. Used carelessly, it can trap you in a cycle of debt that outlasts the original crisis. Understanding what an emergency loan actually is, how it differs from other borrowing options, and when it makes sense to use one will help you make a fast decision you will not regret later.
What Is an Emergency Loan?
An emergency loan is a short-term borrowing product designed to cover an unexpected, urgent expense that cannot wait for your next paycheck or for a traditional bank loan to be processed. The defining characteristics are speed and accessibility. Unlike a mortgage or a standard personal loan from a credit union, which might take days or weeks to fund, an emergency loan can often be approved and deposited within 24 to 48 hours, sometimes the same day.
Emergency loans are not a single product. The term acts as an umbrella covering several loan types, each with different structures, costs, and repayment schedules. The most common include payday loans, which are typically small amounts due on your next payday; installment loans, which are repaid in fixed monthly payments over a set period; and personal loans from online lenders, which can range from a few hundred to several thousand dollars. Some lenders also offer specific emergency products like utility bill loans or auto repair loans. On FreeQuotes.Loans, you can submit a single request and receive offers from multiple third-party lenders, which saves you from filling out dozens of separate applications while a crisis is unfolding.
The critical thing to understand is that an emergency loan is not free money, and it is not a long-term financial solution. It is a bridge. The best emergency loans are those you can repay quickly without damaging your overall financial health. The worst ones stretch your budget so thin that you need another loan to cover the first one, a pattern known as the debt cycle. Recognizing the difference before you sign anything is the single most important step you can take.
How Emergency Loans Differ from Other Borrowing Options
It helps to see emergency loans in context. A traditional personal loan from a bank might offer a lower interest rate, but the application, underwriting, and funding process can take a week or more. A credit card cash advance is fast, but the fees are often steep and the interest rate can be higher than many emergency loans. Borrowing from family or friends avoids interest entirely, but it can strain relationships and is not always an option. An emergency loan occupies a specific niche: faster than a bank, more structured than a credit card swipe, and available to people with less-than-perfect credit.
Here is a quick comparison of the most common emergency borrowing paths:
- Payday loans: Small amounts, typically $100 to $1,000, due in full on your next payday. Fast but expensive if rolled over.
- Installment loans: Slightly larger amounts repaid over several months. More manageable payments but you pay interest for longer.
- Online personal loans: Can range from $1,000 to $50,000 depending on the lender and your qualifications. Best for larger emergencies and stronger credit profiles.
- Credit card cash advances: Immediate access but often comes with a fee of 3 to 5 percent and a higher APR than purchases.
- Borrowing from friends or family: No interest, but potential relationship strain and no formal credit-building benefit.
Each option has a time and a place. The key is matching the tool to the size and urgency of the emergency. A $200 car battery replacement does not require a $10,000 personal loan. A $4,000 medical bill is probably too large for a payday loan to handle responsibly. Knowing your numbers before you apply will help you choose the right product and avoid over-borrowing.
When Should You Actually Use an Emergency Loan?
Not every financial inconvenience qualifies as an emergency. A sale on a TV you have wanted for months is not an emergency. A vacation you failed to budget for is not an emergency. An emergency loan should be reserved for situations where the cost of not having the money is significantly higher than the cost of borrowing it. That means protecting your health, your home, your ability to get to work, or your basic utilities.
Consider these scenarios where an emergency loan is often the right call:
- Medical emergencies: An unexpected surgery, an emergency room visit, or a prescription you cannot afford. Delaying treatment can lead to worse health outcomes and higher costs later.
- Car repairs: If your vehicle is how you get to work, a broken transmission or failed brake system is not negotiable. Missing work can cost you your job.
- Urgent home repairs: A broken furnace in winter, a leaking roof, or a flooded basement. These problems get worse and more expensive the longer they sit.
- Utility shutoff notices: Losing electricity or water creates health and safety risks and can lead to reconnection fees that dwarf the original bill.
- Travel for a family emergency: A sudden death or serious illness in the family may require immediate travel you have not budgeted for.
In each of these cases, the loan is solving a problem that cannot wait. The alternative, whether it is a shutoff, a missed diagnosis, or a lost job, is more costly than the loan itself. That is the test: if the consequence of not borrowing is worse than the cost of borrowing, an emergency loan can be a responsible choice. If the consequence is merely inconvenient or disappointing, it is probably not the right tool.
When You Should Avoid an Emergency Loan
Just as important as knowing when to use an emergency loan is knowing when to walk away. The biggest red flag is borrowing for something that is not truly urgent. If you can wait two weeks and pay cash, wait. If you can negotiate a payment plan with the service provider, do that first. Many hospitals, utility companies, and mechanics offer internal payment plans that cost nothing and do not affect your credit.
Another warning sign is borrowing more than you can reasonably repay. If the loan payment will consume more than a small fraction of your monthly income, you are setting yourself up for trouble. Lenders may approve you for an amount that is technically within their risk tolerance but practically unaffordable for your budget. You are the final gatekeeper. Run the numbers yourself before you accept an offer.
Finally, avoid emergency loans if you are already struggling to make minimum payments on existing debt. Adding another obligation in that situation often accelerates the spiral. In those cases, a debt consolidation loan or a conversation with a nonprofit credit counselor may be a better path. The goal is to solve the emergency without creating a second one.
How to Get an Emergency Loan Fast
Speed matters when you are in a crisis, but so does making an informed decision. The good news is that the process for finding an emergency loan has become significantly more efficient in recent years. Instead of driving to multiple storefront lenders or filling out separate applications on a dozen websites, you can use a comparison service to submit one request and receive multiple offers.
Here is a simple framework for getting funded quickly and responsibly:
- Define the exact amount you need. Borrow only what solves the emergency. Add a small buffer for fees if applicable, but do not round up to a comfortable-sounding number.
- Check your credit score. Knowing where you stand helps you anticipate which offers you will qualify for and what interest rates to expect. A score above 600 opens more doors than many people realize.
- Gather your documents. Most lenders ask for proof of income, a valid ID, and an active bank account. Having these ready speeds up the process.
- Compare multiple offers. Look at the APR, the repayment term, and the total cost of the loan, not just the monthly payment. A slightly longer term with a lower payment might cost more overall.
- Read the terms carefully. Understand the due date, the late fee policy, and whether the lender reports to credit bureaus. These details matter more than the headline rate.
For a streamlined way to compare emergency loan offers from multiple lenders in one place, you can start with a quote comparison for fast funding solutions. This approach saves time and helps you see the full range of options before committing. If you are exploring broader short-term borrowing options, services like AdvanceCash can connect you with lenders who specialize in quick-turnaround loans for people facing immediate financial needs.
What to Check Before You Sign
The excitement of being approved can overshadow the fine print, but this is precisely when you need to slow down. Before you accept any emergency loan offer, verify the following details. First, confirm the APR, not just the interest rate. The APR includes fees and gives you a true picture of the loan's cost. Second, check the repayment schedule. Can you comfortably make the payments on your current income? Third, look for prepayment penalties. Some lenders charge you for paying off the loan early, which is the opposite of what you want. Fourth, confirm whether the lender reports to credit bureaus. On-time payments can help your credit; late payments can hurt it.
Also, be wary of any lender that pressures you to sign immediately without time to review the terms. Legitimate lenders understand that borrowers need to read the agreement. If something feels off, walk away. There is always another lender, and a few extra hours of research can save you hundreds of dollars and months of stress.
Building an Emergency Fund So You Need Fewer Loans
The best time to prepare for an emergency is before it happens. An emergency fund is simply a savings account set aside for unexpected expenses. Financial experts often recommend saving three to six months of living expenses, but that can feel impossible when you are living paycheck to paycheck. Start smaller. Even $500 in a dedicated savings account can cover a car repair or a medical copay and keep you out of the borrowing cycle.
Automate your savings if you can. Set up a recurring transfer of $10 or $20 per week from your checking account to a separate savings account. You will barely notice the money leaving, and within a year you will have a cushion that makes emergencies less financially devastating. The goal is not to eliminate emergency loans entirely, because some crises are simply too large for any savings account. The goal is to reduce how often you need them and how much you need to borrow when you do.
Final Thoughts
An emergency loan is a tool, not a trap, provided you use it for the right reasons and understand the terms. It exists to solve problems that cannot wait: a broken car, a medical bill, a shutoff notice. When the alternative is losing your job, your health, or your home, borrowing can be the responsible choice. But it should always be a deliberate decision, not a panicked one. Compare offers, read the terms, borrow only what you need, and have a plan to repay. Do that, and an emergency loan can do exactly what it is designed to do: get you through the crisis and back on stable ground.