
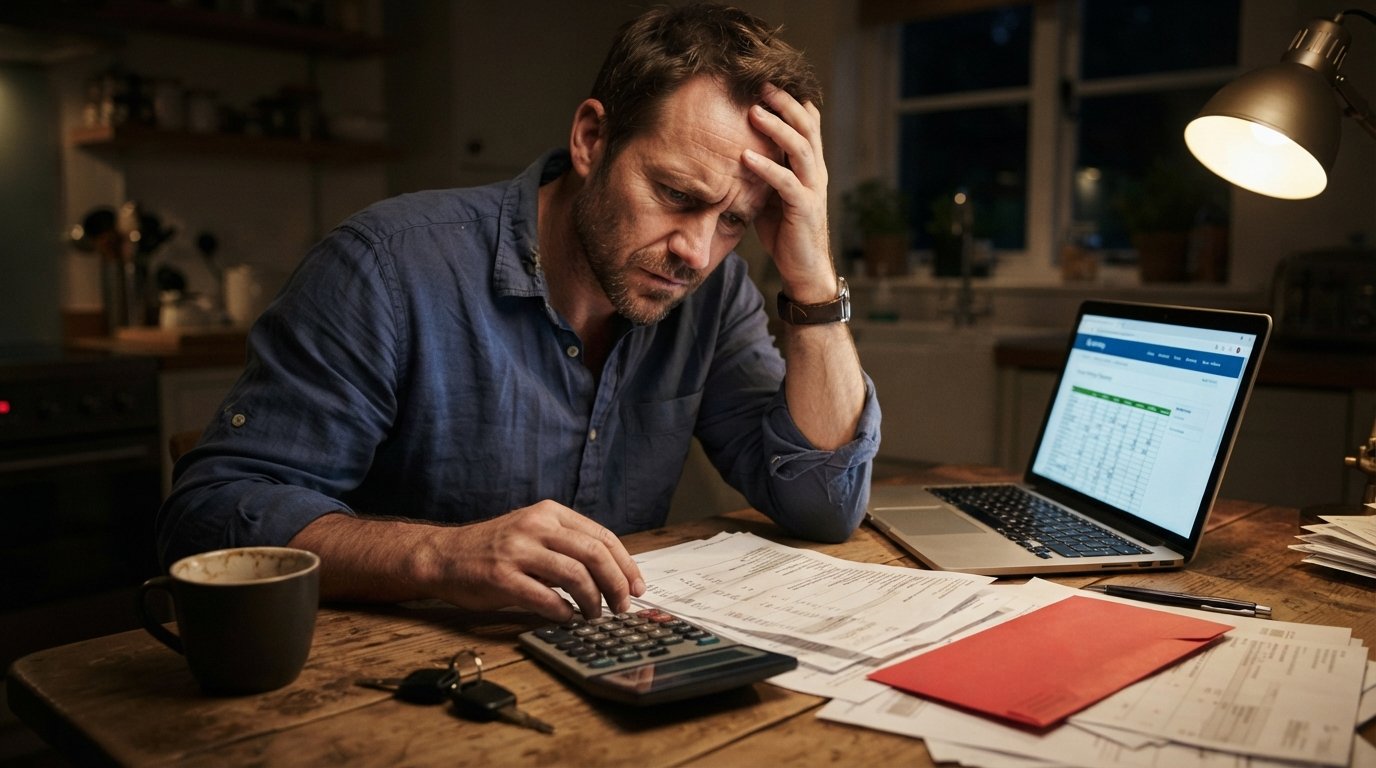
What Happens If You Miss a Loan Payment?
A missed loan payment triggers late fees, credit damage, and possible default. Acting early and communicating with your lender can reduce the harm.
By Grace Shaw
A single missed loan payment can feel like a small stumble, but the ripple effects can reach your credit score, your wallet, and your future borrowing options. Whether you are juggling a payday loan, an installment loan, or a personal loan, understanding the consequences is the first step to protecting yourself. At FreeQuotes.Loans, we connect borrowers with lenders who offer clear terms, but the responsibility for repayment still falls on you. This guide walks you through exactly what happens if you miss a loan payment, from the first late fee to long-term credit damage, and gives you a practical playbook for minimizing harm.
The Immediate Aftermath: Late Fees and Penalty APRs
When your due date passes without a payment, the lender's first response is usually a late fee. This charge can range from $15 to $30 for many personal loans, but payday loans and installment loans may have different structures. For example, a payday lender might charge a fixed fee per $100 borrowed, while an installment lender could assess a percentage of the overdue amount. The key point is that late fees are immediate and often compound if the balance remains unpaid.
Beyond the fee itself, many loan agreements include a penalty APR clause. If you miss a payment, your interest rate can jump to a much higher level, sometimes as high as 29.99% or more. This higher rate may apply to your existing balance and any new charges, making it harder to dig out of debt. Some lenders only apply the penalty APR after two or more missed payments, but others trigger it on the first late payment. Always check your loan contract for the specific terms, because not all lenders handle this the same way.
Another immediate consequence is that your payment may be reported as late to the credit bureaus. Most lenders report to Equifax, Experian, and TransUnion, but typically only after a grace period of 15 to 30 days. If you miss a payment but catch up within that window, the late payment might not appear on your credit report. However, the late fee and any penalty interest will still apply. The grace period is your friend, but it is not a free pass.
How a Missed Payment Damages Your Credit Score
Payment history is the single largest factor in your FICO credit score, accounting for about 35% of the total. A single 30-day late payment can drop a good score by 60 to 100 points, depending on your starting score and the rest of your credit profile. If you already have a fair or poor credit score, the damage may be less severe in absolute points but still significant because you have less cushion to absorb the hit.
The impact does not disappear quickly. A late payment remains on your credit report for seven years from the date of the delinquency. However, its effect on your score diminishes over time, especially if you keep up with payments afterward. The first two years are the most damaging, and lenders may view you as a higher risk during that period. If you are applying for a mortgage, a car loan, or even a new apartment, that late payment could lead to a denial or a higher interest rate.
It is also important to understand the difference between a 30-day late payment and a 60-day or 90-day late payment. The longer you go without paying, the more severe the credit damage. A 90-day late payment can drop your score by 100 points or more and may trigger a default clause in your loan agreement. At that point, the lender might demand the entire remaining balance immediately, which is a financial shock most borrowers cannot absorb.
When Your Loan Goes into Default
Default typically occurs after 90 to 120 days of non-payment, though the exact timeline depends on your loan contract and state law. Once you are in default, the lender has several options. They can accelerate the loan, meaning the full remaining balance becomes due immediately. They can also turn your account over to an internal collections department or sell it to a third-party collection agency. Each of these steps adds more fees and more stress.
If the loan is secured, such as an auto title loan, the lender can repossess the collateral. For unsecured loans like personal loans or payday loans, the lender cannot take your property without a court judgment, but they can sue you. A lawsuit can lead to a wage garnishment, where a portion of your paycheck is taken until the debt is paid. This is a worst-case scenario, but it happens more often than most borrowers realize. The legal costs and court fees are added to what you owe, making the debt even larger.
Collections activity can also be relentless. Debt collectors may call you at work or at home, and they may contact your family members or employer in some cases. While the Fair Debt Collection Practices Act (FDCPA) limits what collectors can do, the stress of constant calls can take a toll on your mental health and your relationships. The sooner you address the missed payment, the more options you have to avoid this outcome.
Steps to Take If You Anticipate Missing a Payment
If you see a financial shortfall coming, do not wait until the due date passes. Proactive communication is your best defense. Lenders are often more willing to work with borrowers who reach out before the payment is late. Here is a simple action plan to follow:
- Contact your lender immediately. Explain your situation and ask about hardship options, such as a deferment, forbearance, or a modified payment plan. Some lenders offer a one-time extension without reporting it to the credit bureaus.
- Review your loan agreement. Look for the grace period, late fee amount, and penalty APR clause. Knowing the exact terms helps you negotiate from a position of knowledge.
- Adjust your budget. Cut non-essential expenses and redirect that money toward the loan payment. Even a partial payment can reduce the late fee and show good faith.
- Set up automatic payments. If you have not already, enroll in autopay to avoid future missed payments. Many lenders offer a small interest rate discount for autopay, which is an added bonus.
- Consider a small side income. A temporary gig, selling unused items, or freelance work can bridge the gap until your next paycheck.
These steps are not a guarantee that your lender will waive fees or protect your credit, but they significantly improve your chances. Lenders want to get paid, and they prefer a cooperative borrower over a delinquent one. If you can show that you are making an effort, you may be able to avoid the harshest consequences.
Communicating with Your Lender About Hardship
Hardship programs are designed for borrowers facing temporary financial difficulties, such as a job loss, medical emergency, or divorce. These programs can include reduced payments, temporary payment pauses, or loan modifications that extend the repayment term. To qualify, you usually need to provide documentation, such as pay stubs, medical bills, or a termination letter. The application process can take time, so start it as soon as you realize you might miss a payment.
When you call your lender, be honest and specific. Explain what caused the hardship, how long you expect it to last, and what you can afford to pay now. Avoid vague statements like "I am having money problems." Instead, say something like "I lost my job last week and I am starting a new one in three weeks. Can we set up a partial payment plan for the next two months?" This level of detail shows that you have thought through your situation and are committed to repaying the loan.
Keep a record of all communication with your lender. Note the date, time, and name of the representative you spoke with, and ask for any agreements in writing. If you cannot reach an agreement, ask to speak with a supervisor or a hardship specialist. Some lenders have dedicated teams for this purpose, and they may have more flexibility than the front-line customer service agents. Remember that you are not the first borrower to face this situation, and most lenders have a process in place.
How to Get Back on Track and Avoid Future Misses
Once you have missed a payment, the priority is to get current as quickly as possible. Pay the overdue amount plus any late fees, and then resume your regular payment schedule. If you cannot pay the full overdue amount at once, ask your lender if you can split it into smaller payments over the next few weeks. Some lenders will agree to this if you have a good payment history and you communicate clearly.
After you are current, focus on building a financial buffer so that a future surprise does not derail you again. A common approach is to set aside a small amount from each paycheck into a savings account, even if it is just $20 or $50. Over time, this emergency fund can cover a car repair or a medical bill without forcing you to miss a loan payment. You can also look for ways to increase your income or reduce your fixed expenses, which gives you more breathing room each month.
Another smart move is to consolidate high-interest debt into a lower-interest personal loan. If you are juggling multiple payments, a single loan with a fixed rate and a predictable due date can simplify your finances and reduce the risk of missing a payment. When comparing offers, pay attention to the APR, origination fees, and repayment terms. FreeQuotes.Loans can help you request quotes from multiple lenders with a single form, which saves time and gives you a clearer picture of your options. For general guidance on managing loan quotes, see our article on what happens when your loan quote expires.
Finally, consider setting up payment reminders on your phone or calendar. A simple alert three days before the due date can be enough to prevent an accidental miss. If your income is irregular, try to schedule payments for a time of the month when you are most likely to have funds available. Some lenders allow you to change your due date, so ask if that is an option.
The Role of Loan Comparison Services in Responsible Borrowing
Missed payments often happen because borrowers take on more debt than they can comfortably repay. That is why it is important to compare loan offers and choose terms that fit your budget. A loan comparison service like FreeQuotes.Loans does not lend money directly, but it connects you with a network of third-party lenders who may offer different rates, fees, and repayment schedules. By submitting one request, you can see multiple offers and pick the one that aligns with your income and expenses.
When you use a comparison service, remember that the lender, not the service, sets the final terms. Always read the loan agreement carefully before signing. Look for the APR, the total cost of the loan, the late fee policy, and the grace period. If you have a less-than-perfect credit score, you may be offered a loan with a higher interest rate. That is not necessarily a bad thing if it helps you cover an emergency, but you should have a plan to repay it on time. Borrowing responsibly means understanding the cost of the loan and being confident that you can meet the payments.
If you are exploring short-term options, you might also consider 4Payday, a financial services website that connects consumers with lenders offering payday loans, personal loans, and installment loans. Like any loan, these products come with risks, and missing a payment can lead to the same consequences described in this article. The key is to borrow only what you need and to have a clear repayment plan from day one.
Key Takeaways: Protecting Yourself After a Missed Payment
To summarize, a missed loan payment triggers late fees, potential penalty APRs, and credit score damage that can last for years. The severity depends on how quickly you act. If you communicate with your lender before the due date, you may be able to avoid the worst outcomes. If you have already missed a payment, get current as soon as possible and ask about hardship programs. Building an emergency fund and using autopay can help you avoid future misses.
Remember that you are not alone. Many borrowers face temporary setbacks, and lenders have processes to help. The most important step is to take action early rather than ignore the problem. By staying informed and proactive, you can minimize the damage and get back on the path to financial stability.