
Utility Bill Loan for Overdue Payments: How It Works
A utility bill loan for overdue payments can stop a shutoff fast. See how it works, what it costs, and how to apply through FreeQuotes.Loans.
By Laura Carter
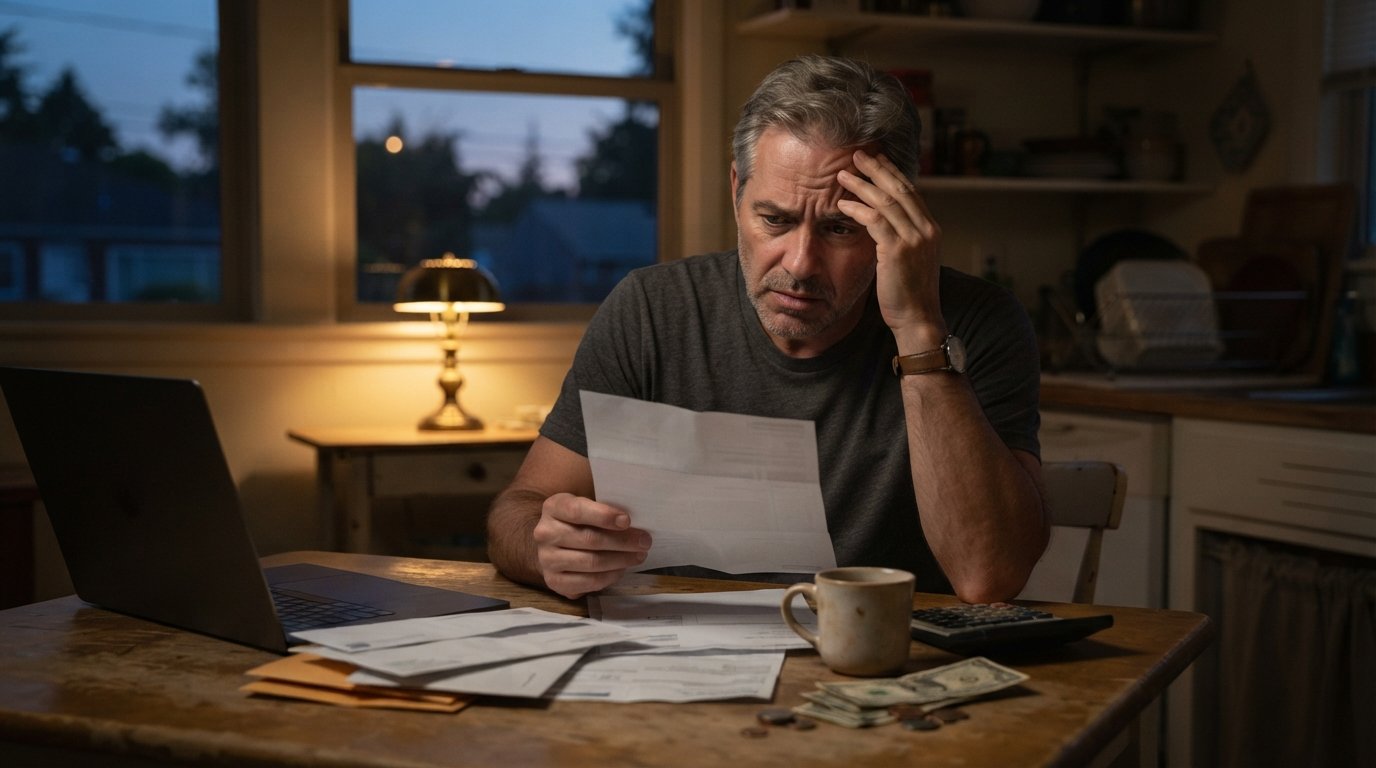
Your electricity is scheduled for disconnection in three days, and the overdue balance is more than you can cover before the shutoff notice takes effect. A utility bill loan for overdue payments can bridge that gap, but only if you understand the costs, the timeline, and the repayment obligations before you sign. This guide explains how these loans work, what to expect from the application process, and how to decide whether borrowing is the right move for your situation.
What Is a Utility Bill Loan and How Can It Prevent Disconnection?
A utility bill loan is a short-term borrowing product designed to cover past-due balances on essential services like electricity, gas, water, or sewer. When you face a shutoff notice, the utility company typically requires payment in full or a formal payment arrangement before service continues. A loan gives you the cash to satisfy that requirement immediately, preserving your access to power and water while you repay the lender over an agreed schedule.
These loans are not a government program or a utility company hardship fund. They are consumer credit products offered by third-party lenders, and they carry interest and fees just like any other loan. The key distinction is purpose: you are borrowing specifically to clear an overdue utility balance, not for discretionary spending. Lenders may ask what the funds are for, though many short-term lenders do not require detailed documentation of the bill itself.
The disconnection prevention angle is critical. Once service is cut off, reconnection often involves additional fees, a deposit, and a wait of several days. A loan that clears the overdue balance before the shutoff date avoids those extra costs and restores your account to good standing. However, the loan only solves the immediate crisis. If your underlying budget cannot support both the loan repayment and your ongoing utility costs, you may find yourself in a similar position next month.
Typical Loan Amounts, Terms, and Costs
Utility bill loans generally range from $100 to $1,000, though some personal loan products can go higher depending on the lender and your qualifications. The amount you qualify for depends on your income, credit profile, and the lender's underwriting criteria. Most borrowers seek just enough to cover the overdue balance plus any late fees, which keeps the loan small and the repayment manageable.
Terms vary widely by loan type. Payday loans, which are common for utility emergencies, typically come due on your next payday, usually within two to four weeks. Installment loans spread repayment over several months, which can make the monthly obligation smaller but increases the total interest paid. Personal loans from online lenders may offer terms of six to twenty-four months with fixed monthly payments.
Costs are the most important factor to evaluate. Short-term loans can carry annual percentage rates (APRs) that exceed 300 percent when fees are annualized. A $300 loan with a $45 fee due in two weeks has an APR well above 300 percent. Installment loans and personal loans usually have lower APRs, but they still represent real money. Before you borrow, calculate the total repayment amount, not just the monthly payment, and compare it to the cost of a payment plan with your utility company.
Here are the key cost components to review in any loan offer:
- Interest rate or finance charge (the cost of borrowing)
- Origination or application fees (some lenders waive these)
- Late payment penalties and their impact on your credit
- Prepayment penalties (rare, but check the fine print)
- Total repayment amount over the life of the loan
Understanding these costs helps you compare offers accurately. A loan with a lower monthly payment but a longer term may cost more overall than a shorter, higher-payment loan. The best choice depends on your cash flow and how quickly you can repay without straining your budget.
How to Apply Through FreeQuotes.Loans and Get Matched with Lenders
FreeQuotes.Loans is not a direct lender. It is an online loan comparison and connection service that matches borrowers with third-party lenders who may offer utility bill loans and other short-term products. The process is designed to be fast and entirely online, typically taking under five minutes to submit a request. You fill out a single form with basic information about yourself, your income, and the amount you need, and the platform routes your request to lenders in its network.
To apply, you generally need to meet a few basic requirements: you must be at least 18 years old, have a valid form of identification, an active bank account, and a steady source of income. Income can come from employment, self-employment, government assistance, disability payments, or a pension. The platform does not charge a fee for its connection service, and submitting a request does not obligate you to accept any offer.
Here is how the process works step by step:
- Visit the FreeQuotes.Loans website and complete the online request form with your basic details and the amount you need to cover the overdue utility bill.
- Submit the form and wait for the platform to match your request with lenders in its network (this often happens within minutes).
- Review the loan offers you receive, paying close attention to the APR, fees, repayment terms, and any conditions.
- Choose the offer that best fits your situation and complete the lender's application and verification process.
- Receive funds, often as soon as the next business day, and use them to pay the overdue utility balance before the shutoff date.
After you submit your request, you may receive multiple offers from different lenders. This is the main advantage of using a connection service: you can compare several options side by side rather than applying to each lender individually, which would generate multiple credit inquiries. Keep in mind that the lenders, not FreeQuotes.Loans, set all loan terms, rates, and approval decisions. If you are unsure whether you can back out after accepting an offer, it helps to know how to reject a loan after approval and what your rights are during the process.
For borrowers with less-than-perfect credit, the platform's network includes lenders who work with a range of credit profiles. Approval is never guaranteed, but a steady income and an active bank account improve your chances. If you are exploring short-term borrowing options, you can also review additional resources at AdvanceCash to understand how loan-connection services work and what to expect from the application process.
Alternatives to Borrowing: Payment Plans and Assistance Programs
Before you take on debt, explore the options available directly through your utility company. Most utilities offer payment arrangements that spread an overdue balance over several months, often without interest. These plans are designed to keep your service on while you catch up gradually. Contact your utility's customer service department as soon as you receive a shutoff notice; the earlier you call, the more options you typically have.
Beyond payment plans, many states and local agencies administer Low Income Home Energy Assistance Program (LIHEAP) funds and other hardship programs that can help cover past-due bills. Eligibility depends on income, household size, and the specific program. Community action agencies and charitable organizations may also offer one-time grants. These options do not require repayment and should be exhausted before you consider a loan.
If you have already explored payment plans and assistance and still face a gap, a loan may be the remaining option to avoid disconnection. But compare the cost of borrowing to the cost of reconnection. In some cases, letting service lapse briefly and paying the reconnection fee may be cheaper than a high-APR loan, though this depends on your utility's policies and the time of year. Weigh the trade-offs carefully, especially if you have medical equipment that requires power or young children in the home.
Responsible Borrowing: Only Borrow What You Can Repay
The most important rule of utility bill lending is simple: borrow only what you need to clear the overdue balance and can realistically repay on time. It is tempting to round up the loan amount to cover next month's bill as well, but that increases your debt and the cost of borrowing. A smaller loan with a clear repayment plan is almost always the better choice.
Before you accept an offer, build a simple repayment plan. Look at your income and fixed expenses, and confirm that the loan payment fits without forcing you to skip other obligations. If the payment would consume more than a small percentage of your monthly income, the loan may create more problems than it solves. Missing a payment can damage your credit score, trigger late fees, and lead to collection activity, which is a far worse outcome than negotiating a payment plan with your utility in the first place.
Also consider the long-term picture. A utility bill loan addresses an emergency, but it does not fix the underlying budget gap. If overdue bills are a recurring problem, the solution lies in budgeting, energy assistance, or restructuring your expenses, not in repeated borrowing. Use a loan as a one-time bridge, and pair it with a plan to keep future bills current. That approach protects your credit, your utility service, and your financial stability.
Utility bill loans can prevent a shutoff and buy you time, but they are not free money. Understand the terms, compare offers, and borrow with a clear repayment plan in mind. If you decide to move forward, start by exploring your options through a connection service that lets you compare multiple lenders in one place, and always confirm the final terms with the lender before you sign.