
Microloans for Small Emergency Expenses Explained
Microloans for small emergency expenses explained: get $100 to $1,000 fast for urgent bills. Call 8335013363 to compare offers and avoid costly rollovers.
By Irene Young
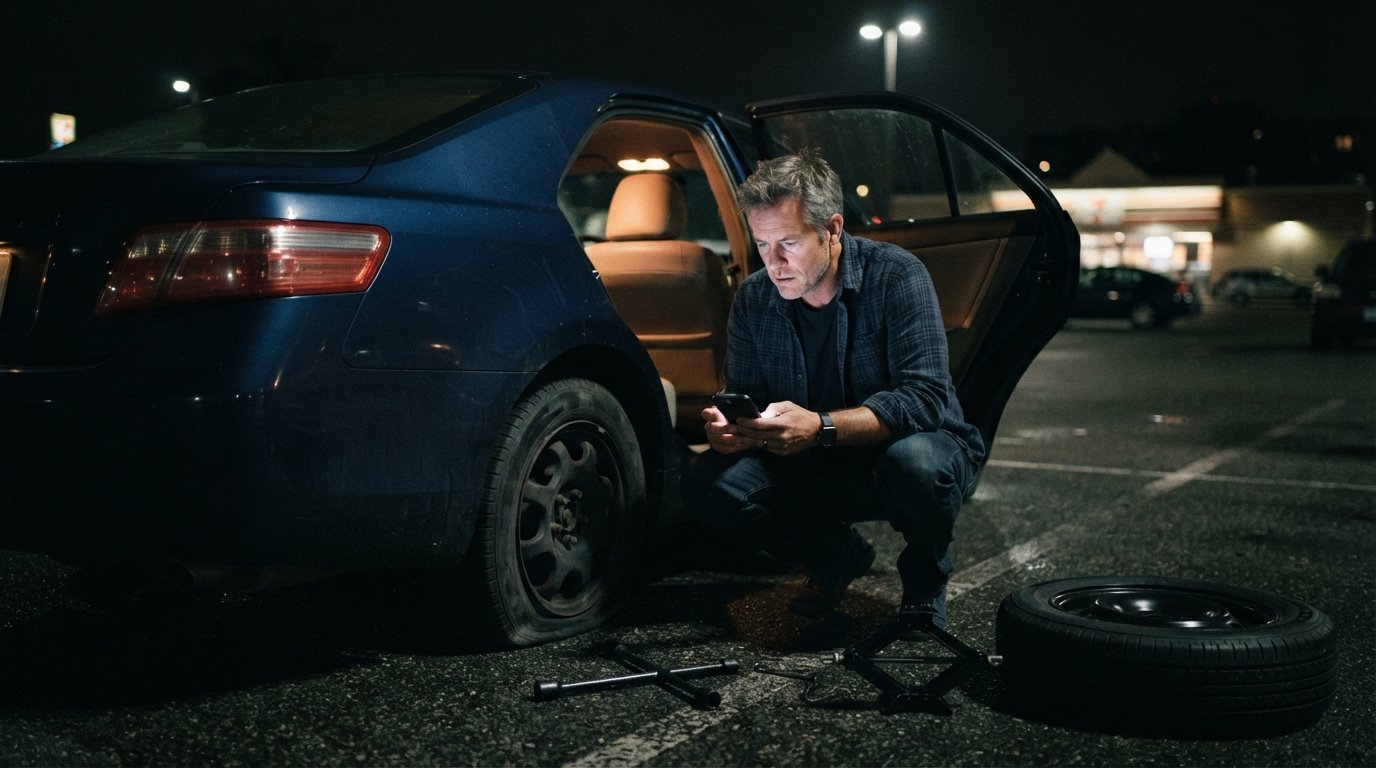
A flat tire at 11 p.m. A sudden co-pay you did not budget for. A utility notice warning of a shutoff in three days. These moments rarely announce themselves, and they rarely arrive when your bank account is ready. That is exactly why microloans for small emergency expenses have become a practical tool for millions of Americans who need a modest amount of cash quickly, without the paperwork marathon of a traditional bank loan. Understanding how these small loans work, what they cost, and where to find them can mean the difference between a temporary setback and a financial spiral.
What Exactly Is a Microloan?
The term microloan originally described tiny business loans, often under $50,000, made to entrepreneurs in developing economies who lacked access to traditional banking. In the United States today, the word has broadened. When people talk about microloans for small emergency expenses, they usually mean short-term consumer loans in the $100 to $1,000 range, sometimes stretching to a few thousand dollars, designed to cover one specific, urgent cost. The defining features are the small principal, the fast timeline, and the simplified application.
This is different from a standard personal loan of $10,000 that you might spread over five years. A microloan is sized to the problem. If your car needs a $400 repair and you will have the money in two weeks, borrowing $10,000 makes no sense. Borrowing $400 to $500 does. That proportionality is the entire point, and it is why these products sit in a category of their own.
It helps to think of microloans as sitting on a spectrum. On one end are payday loans, typically $100 to $1,000, due on your next payday. In the middle are installment loans, repaid in fixed monthly chunks over several months. On the other end are smaller personal loans from online lenders, which can look and behave much like conventional loans but with faster underwriting. The right fit depends on how much you need, how quickly you can repay, and how much total cost you can absorb.
Why Small Emergency Expenses Are a Different Problem
Emergency expenses have three qualities that make them awkward for traditional lending. They are urgent, they are specific, and they are usually small. A bank wants to underwrite a loan over days or weeks, verify employment and income, and charge an origination fee that only makes sense on a larger principal. None of that fits a $300 water heater replacement that needs to happen tomorrow.
That mismatch creates real consequences. Many households do not have $400 in cash for an unexpected expense, according to years of Federal Reserve survey data. When the only options are a credit card near its limit, a late fee, or a shutoff notice, a small loan can be the least damaging path. The key word is "least damaging." A microloan is not free money, and it is not a long-term fix for a budget that does not balance. It is a bridge across a short gap.
Common situations where a microloan makes sense include:
- An urgent medical or dental bill that cannot wait for a payment plan
- A car repair that stands between you and your job
- An overdue utility bill with a disconnection date attached
- A necessary home repair, such as a broken furnace in winter
- A short gap between paychecks caused by an unexpected expense
Notice what is not on that list: vacations, holiday shopping, or routine bills you simply forgot to plan for. Those are budgeting issues, not emergencies. The distinction matters because microloans carry a higher cost per dollar than most other credit, and using them for non-emergencies is how borrowers get into trouble.
How Microloans Work, Step by Step
The mechanics are simpler than most people expect. You submit a request online, a lender or network evaluates it, you receive an offer, and if you accept, funds are deposited into your bank account. The entire sequence can happen in a single day, and sometimes in a few hours. Here is the typical flow.
- Submit a short request. You provide basic details: name, contact information, income source, bank account, and the amount you need. This usually takes under five minutes.
- Get matched or reviewed. Some services connect you with a network of lenders. Others, like LendersCashLoan, act as a connection service, passing your request to third-party lenders who may extend an offer.
- Review the offer carefully. You will see the amount, the APR, the repayment schedule, and any fees. This is the moment to slow down and read.
- Accept and receive funds. If you agree to the terms, the lender deposits money into your account, often as soon as the next business day.
- Repay on schedule. Depending on the product, you repay in a lump sum on your next payday or in fixed installments over weeks or months.
One detail that surprises many first-time borrowers is how much weight the application places on your income and bank account rather than your credit score. Many lenders in this space welcome applicants with less-than-perfect credit, provided they can show steady income and an active checking account. That said, the lender will still review your history, and the inquiry itself can show up on your credit report. In our guide on hard inquiry vs soft inquiry loan quotes, we explain how different types of credit checks affect your score, which is worth reading before you submit multiple applications.
What Microloans Cost and Why the APR Looks So High
Here is the part that deserves your full attention. A microloan's annual percentage rate, or APR, often looks shocking compared to a mortgage or auto loan. You may see figures like 200%, 400%, or higher on payday-style products. That number is real, and you should take it seriously. But it also reflects the mathematics of short terms. A $15 fee on a $100 two-week loan translates to a very high annual rate, even though the dollar cost is modest.
The practical takeaway is to compare offers by total dollars repaid, not just the APR headline. If you borrow $300 and repay $345 two weeks later, your cost is $45. That may be acceptable if the alternative is a $75 late fee plus a damaged credit score. It is not acceptable if you will need to borrow again next month to cover the repayment. Rolling a microloan into a new loan is the single most common way small debts become large ones.
Costs to watch for include:
- Finance charges or fees added to the principal
- Origination fees deducted from the amount you receive
- Late fees if a payment misses its due date
- Prepayment penalties in rare cases, though many lenders allow early payoff
- NSF fees from your own bank if a scheduled debit bounces
Before accepting any offer, ask one question: if everything goes wrong, what is the maximum I could owe? If that number is not survivable, the loan is too big for your situation. Shrinking the request is almost always smarter than stretching to cover it.
Where to Find Microloans for Small Emergency Expenses
There are more sources than most people realize, and they vary widely in cost and speed. The fastest options are online, but the cheapest options are often local. A smart borrower checks at least two or three before committing.
Online loan connection services are the most common starting point for urgent needs. You submit one request and receive multiple offers from third-party lenders, which saves you from filling out a dozen separate applications. FreeQuotes.Loans operates this way: it is not a direct lender, it does not charge you a fee for the connection, and it matches your request with lending partners who may offer payday loans, personal loans, installment loans, or emergency loans ranging from $100 to $50,000. Because one request can generate several offers, you can compare terms side by side rather than accepting the first number you see.
Other sources worth knowing include credit unions, which offer small personal loans and payday alternative loans at far lower rates but usually require membership and a day or two of processing. Employer advances are another option; some companies let you draw against earned wages. Family and friends remain the cheapest source of all, though mixing money and relationships carries its own cost. Finally, community organizations and local charities sometimes provide small emergency grants, particularly for utility bills, that do not need to be repaid at all.
How to Qualify and What Lenders Look For
Qualification for a microloan is deliberately simple, but it is not automatic. Lenders want evidence that you can repay, and they want a reliable way to collect. Meeting the basic requirements does not guarantee approval, and no honest service will promise you one.
The standard requirements look like this:
- You are at least 18 years old
- You have valid government-issued identification
- You have an active bank account, usually a checking account
- You can show a steady source of income, which may include employment, self-employment, disability, a pension, or government assistance
- You can provide a phone number and email address for verification
Beyond the checklist, lenders consider the shape of your finances. A steady paycheck of modest size often beats irregular income of a larger size, because predictability matters more than volume. A bank account without a history of overdrafts signals stability. And a request that matches your income, say $300 when you take home $2,000 a month, looks far better than $2,000 when you take home $800. If you are declined, ask why. Sometimes the fix is as simple as reducing the amount or waiting until a recent deposit clears.
The Risks You Should Understand Before Borrowing
A microloan is a financial tool, and like any tool, it can help or hurt depending on how it is used. The risks are well documented, and understanding them in advance is the best protection you have.
The first risk is the rollover trap. If you cannot repay on the due date and the lender offers to extend the loan for another fee, you may find yourself paying the fee again and again while the principal never shrinks. A $300 loan can cost $600 or more over a few months without ever being paid off. The second risk is credit damage. Missing a payment or defaulting can be reported to credit bureaus, lowering your score and making future borrowing more expensive. The third risk is the bank account drain: many lenders use automatic debits, and a failed debit can trigger overdraft fees from your own bank on top of the lender's late fee.
None of this means you should never take a microloan. It means you should take one only when you have a clear, realistic plan for repayment, ideally tied to a specific upcoming deposit. If your plan depends on something that might not happen, the loan is a gamble, not a bridge.
Smart Borrowing Checklist for Small Emergencies
Use this checklist before you accept any microloan offer. It takes five minutes and can save you hundreds of dollars.
- Confirm the expense is truly urgent and unavoidable.
- Borrow the smallest amount that solves the problem, not a round number that feels comfortable.
- Compare at least two offers, looking at total repayment, not just the monthly or per-paycheck figure.
- Check the repayment date against your actual pay schedule, including any lag between payday and deposit.
- Ask whether early repayment is allowed without penalty, and whether partial payments are accepted.
- Set a reminder two days before the due date so a debit never surprises you.
- Write down your payoff plan on paper or in your phone, including the exact source of the money.
If you cannot complete step seven with confidence, step one deserves a second look. There may be a cheaper path, such as a payment plan with the service provider, a small grant, or a short-term arrangement with family.
Alternatives Worth Considering First
Microloans are fast, but they are rarely the cheapest option. Before you borrow, spend ten minutes checking whether one of these alternatives fits your situation better.
Ask the creditor for more time. Hospitals, utility companies, and repair shops frequently offer internal payment plans that cost nothing extra. A five-minute phone call can convert a crisis into a schedule. Credit cards, if you have available limit, are usually cheaper than payday-style products for short-term needs, though the interest still accrues. A credit union payday alternative loan can cut your cost dramatically if you can wait a day or two. And for utility bills specifically, many states have assistance programs that pay a portion of the balance to prevent shutoffs.
The right order of operations is simple: free options first, cheap credit second, fast microloans last. When you do reach for a microloan, choose a connection service that shows you multiple offers at once, read every term, and repay as fast as the loan allows. Used that way, a small loan is exactly what it should be: a short bridge to the next paycheck, not a new monthly bill.