
How to Use a Small Personal Loan to Cover a Car Repair
A small personal loan can cover an unexpected car repair fast. See how to compare offers, avoid overpaying, and get back on the road with a plan.
By Miles Kensington
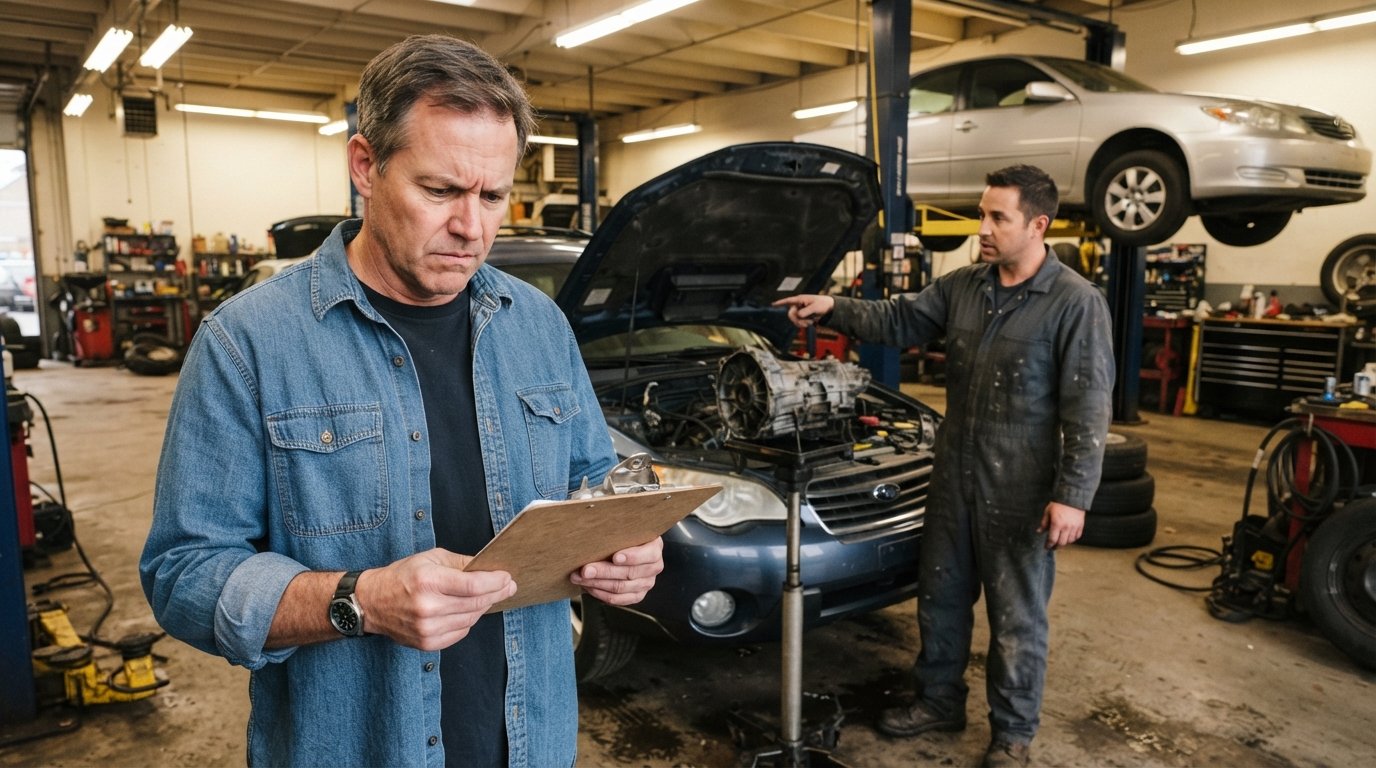
A sudden transmission failure. A cracked radiator. A check engine light that turns into a $1,800 estimate before lunch. When your car breaks down, you rarely have the luxury of waiting for the next payday, and the repair shop will not hold your spot while you shuffle money between accounts. For many drivers in the United States, a small personal loan is the most practical bridge between a broken vehicle and a working one. The key is knowing exactly how to use a small personal loan to cover a car repair in a way that fixes the car without wrecking your monthly budget.
This guide walks through the entire process, from deciding whether a loan is the right move, to comparing offers, to repaying the balance without damaging your credit. FreeQuotes.Loans is an online loan comparison and connection service, not a direct lender, and it was built for exactly this kind of urgent situation: a single request form, multiple third-party lending partners, and potential funding as soon as the next business day. If you are staring at a repair estimate you cannot cover today, the steps below will help you move forward with clarity instead of panic.
Why Car Repairs Push So Many Budgets Over the Edge
Vehicle repairs sit in a frustrating category of expenses: they are unpredictable, they are rarely optional, and their cost keeps climbing. According to industry data, the average cost of a major repair, such as replacing a transmission or a catalytic converter, routinely runs into the thousands of dollars. Even moderate jobs like brake replacements, alternator swaps, or air conditioning fixes can land between $400 and $1,200. Most households do not keep that kind of money sitting in a checking account, and a 2024 survey found that a large share of American adults could not cover a $1,000 emergency from savings.
What makes car repairs uniquely stressful is the transportation trap. You need the car to get to work, to take children to school, to attend medical appointments. A delay of even two or three days can cost you wages, childcare, or both. That urgency is exactly why a small personal loan can be a smarter move than waiting, borrowing from a high-interest credit card at a cash advance rate, or using a title loan that puts your vehicle itself at risk. A personal loan gives you a fixed sum, a fixed repayment schedule, and a clear finish line.
That said, a loan is not automatically the right answer. If the repair costs more than the car is worth, or if the repair is one of several major issues on the horizon, financing the fix may only delay a bigger decision. Before you borrow, get a written estimate from the shop, ask whether a used or refurbished part is available, and confirm there are no additional issues waiting behind the one you already know about. A second opinion from another shop costs little and can save hundreds.
How to Use a Small Personal Loan to Cover a Car Repair: A Step-by-Step Framework
Once you have decided that borrowing makes sense, the process becomes much more manageable. The goal is not just to get money fast, but to get the right money on the right terms. Follow these steps in order, and you will avoid the most common mistakes borrowers make when they are under pressure.
- Confirm the exact repair cost in writing. Ask the shop for an itemized estimate that separates parts from labor. This number becomes your borrowing target, plus a small buffer for tax, shop supplies, or a surprise discovered once the vehicle is on the lift.
- Check your credit and your budget. Pull a free credit report, note your score range, and calculate how much monthly payment you can comfortably absorb without falling behind on rent, utilities, or groceries. A loan payment should not exceed roughly 5 to 10 percent of your monthly take-home pay.
- Submit one request to a loan connection service. Instead of applying to five lenders and triggering five hard credit inquiries, use a single form through a service like FreeQuotes.Loans to see multiple offers from third-party lending partners.
- Compare the offers side by side. Look at the APR, the total repayment cost, the loan term, and any origination or prepayment fees. The lowest monthly payment is not always the cheapest loan.
- Accept the best offer and receive funds. Once you e-sign and verify your bank account, funds can arrive as soon as the next business day, which is usually fast enough to get your car back on the road.
Notice that the first two steps do not involve any lender at all. That is intentional. Borrowers who know their number and their budget before they see offers are far less likely to accept a loan that feels affordable in the moment but becomes a burden three months later. Speed matters when your car is in the shop, but a few extra minutes of preparation can save you hundreds of dollars over the life of the loan.
Choosing the Right Loan Type for a Car Repair
The phrase "personal loan" covers several distinct products, and the one you choose should match the size of the repair and how quickly you can repay it. For a $300 to $1,000 repair, such as a battery, alternator, or brake job, a short-term payday loan or a small installment loan may be sufficient, though payday loans carry very high fees and should be used only when no better option exists. For repairs between $1,000 and $5,000, such as a transmission replacement or major engine work, an installment loan or a standard personal loan is usually the better fit because it spreads repayment over several months with a predictable monthly payment.
If the repair is larger, or if you also need to cover related costs like a rental car while yours is in the shop, a personal loan with a higher limit may be appropriate. Through FreeQuotes.Loans, loan amounts range from $100 up to $50,000 depending on the loan type and the individual lender's criteria. That flexibility matters: you can request only what you need for the repair rather than over-borrowing and paying interest on money you did not use. For readers who want to understand how multiple offers stack up before committing, our guide on comparing personal loan estimates explains how to read quotes side by side and spot the real cost differences.
One more consideration: some repair shops offer their own financing through a third-party partner. These can be convenient, but the rates are not always competitive, and the application may be submitted before you have had a chance to compare. It is almost always worth spending five minutes submitting a request through a comparison service first, so you know what the market looks like before you sign anything at the counter.
What Lenders Actually Look At When You Apply
Understanding the lender's perspective helps you present yourself in the best possible light. Most lenders that fund small personal loans for car repairs evaluate four things: your income, your credit history, your debt-to-income ratio, and your banking history. A stable source of income is often the single most important factor, and it does not have to come from a traditional employer. Self-employment income, disability payments, pensions, and government assistance can all count, provided you can document them.
Credit history matters, but it is not the only gatekeeper. Many lending partners in the FreeQuotes.Loans network work with borrowers who have less-than-perfect credit, including those with past bankruptcies or prior vehicle repossessions. What these lenders are really asking is whether you can realistically repay the loan on time given your current income. If your credit score is low but your income is steady and your existing debts are modest, you may still receive offers, though the APR will likely be higher than what a prime borrower would see.
Before you apply, gather the documents most lenders request: a government-issued ID, proof of income (pay stubs, bank statements, or benefit letters), an active checking account, and your Social Security number. Having these ready speeds up the process and reduces the chance that a lender withdraws an offer because verification took too long. If you are exploring broader short-term borrowing options, services like AdvanceCash also connect U.S. consumers with third-party lenders for payday, personal, and installment loans, which can be useful context when you are comparing how different connection platforms structure their request forms and lender networks.
How to Compare Offers Without Getting Burned
When several offers land in your inbox within minutes, the temptation is to grab the first one with a monthly payment you recognize. Resist that impulse. The true cost of a loan is the total amount you will repay, not the size of the monthly installment. A loan with a lower monthly payment but a much longer term can cost you hundreds more in interest over time. Conversely, a slightly higher monthly payment on a shorter term may save you significant money if your budget can handle it.
Here are the factors that deserve the most attention when you compare offers:
- APR: This is the annualized cost of the loan including interest and most fees. It is the single best number for comparing offers of different sizes and terms.
- Total repayment amount: Multiply the monthly payment by the number of payments. That is what the loan actually costs you.
- Loan term: Shorter terms mean higher payments but less total interest. Longer terms mean lower payments but more total cost.
- Fees: Look for origination fees, prepayment penalties, and late payment charges. A loan with no prepayment penalty lets you pay it off early and save interest.
- Funding speed: If your car is in the shop, when the money arrives matters. Confirm whether funds arrive by next business day, same day, or within several days.
It also helps to check whether the lender reports to the major credit bureaus. On-time payments on a personal loan can gradually improve your credit score, which is a real long-term benefit. Missing payments, on the other hand, can damage your credit and lead to collection activity. Treat the repayment schedule as a fixed obligation from the day you accept the offer, not as something you will figure out later.
Repaying the Loan Without Derailing Your Finances
The repair is done, the car is back in your driveway, and now the real work begins: paying the loan back on schedule. The most reliable approach is to automate the payment so it comes out of your account on a date that lines up with your paycheck. If your pay schedule is irregular, contact the lender before you miss a payment to discuss options; most would rather adjust a due date than send an account to collections. Late payments can trigger fees, hurt your credit score, and in some cases accelerate the entire balance.
If your financial situation improves, consider paying the loan off early, but only after confirming there is no prepayment penalty. Eliminating the balance reduces the total interest you pay and frees up monthly cash flow. If your situation worsens, do not ignore the problem. Reach out to the lender, explain the circumstances, and ask about hardship programs, deferments, or modified payment plans. Silence is the one response that reliably makes things worse.
Finally, use the repair as a prompt to build a small emergency fund. Even setting aside $25 per week creates a cushion that can cover the next unexpected bill, whether it is a tire, a tooth, or a water heater. The goal is not to never borrow again, but to borrow from choice rather than desperation. A small personal loan used wisely can solve a real problem today and, with a bit of planning, leave you in a stronger position tomorrow.
Car repairs are never convenient, but they do not have to be financially devastating. By confirming the cost, checking your budget, comparing multiple offers through a connection service, and repaying on schedule, you can turn a stressful breakdown into a manageable event. The right small personal loan covers the repair, protects your ability to get to work, and keeps your credit on solid ground, which is exactly what a financial tool should do when you need it most.