
How to Handle Debt Collection Calls About a Defaulted Loan
Learn how to handle debt collection calls about a defaulted loan. Know your rights, verify the debt, and negotiate a resolution that protects your finances.
By Miles Kensington
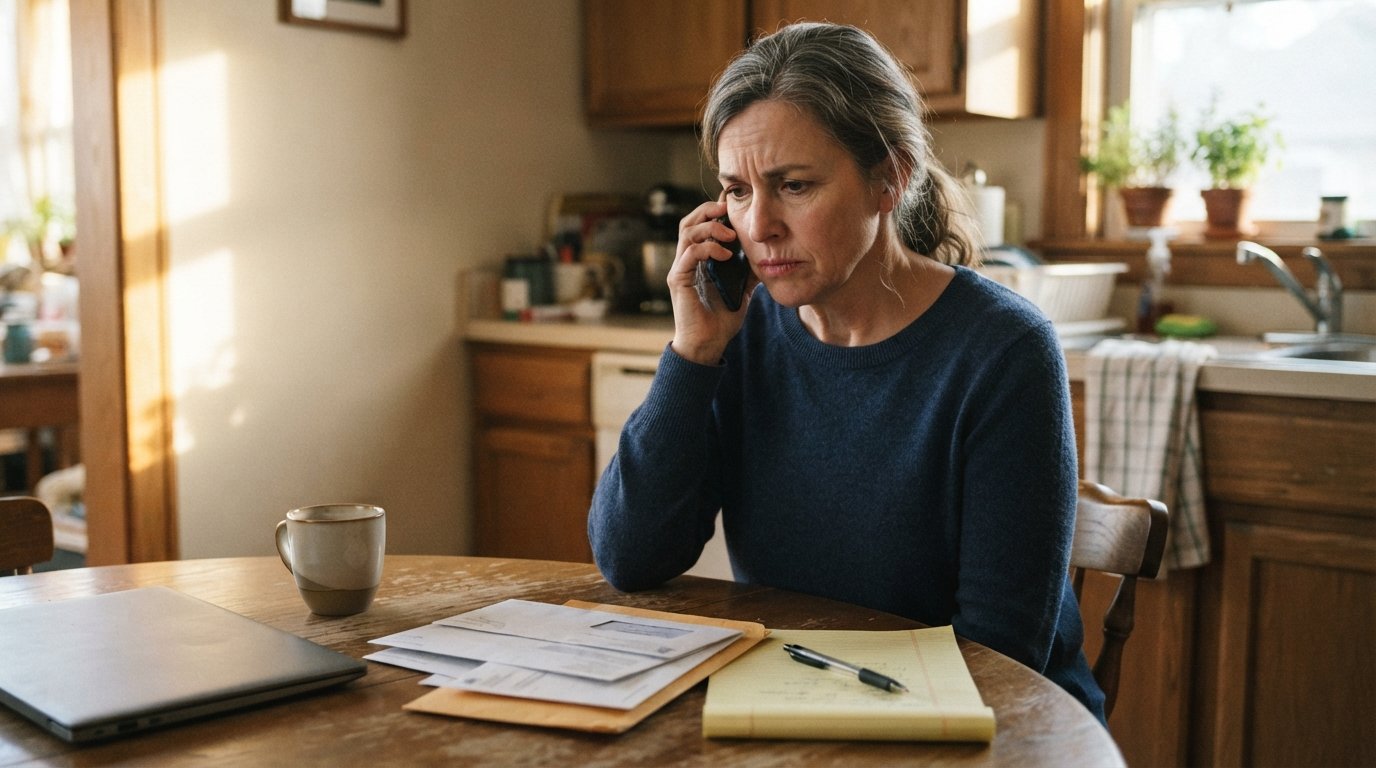
Your phone rings, and the number is unfamiliar. You answer, and a voice on the other end says you owe money on a loan you defaulted on. Your stomach drops. Maybe you have been avoiding this call for weeks, or maybe it is the first time a collector has reached you. Either way, the pressure is real, and the stakes feel high. Knowing how to handle debt collection calls about a defaulted loan can mean the difference between a manageable resolution and months of stress, damaged credit, and legal worry.
The good news is that you have rights, options, and leverage. Federal law protects you from abusive collection tactics, and there are practical steps you can take to regain control of the conversation. Whether the debt is valid, whether you can pay it, or whether you need time to figure things out, you do not have to navigate this alone or unprepared. This guide walks you through exactly what to do when collectors call, how to protect yourself, and how to move toward a resolution that fits your financial reality.
Understand Who Is Calling and What They Can Legally Do
Before you can respond effectively, you need to know who is on the other end of the line. Debt collectors are not all the same. Some are original creditors trying to recover their own money. Others are third-party collection agencies that bought your debt for pennies on the dollar and now want to collect the full balance. Still others are debt buyers who may have incomplete or inaccurate records. Knowing which type you are dealing with helps you set expectations and respond strategically.
The Fair Debt Collection Practices Act (FDCPA) governs how third-party collectors can behave. It does not cover original creditors in every situation, but many states have their own laws that extend similar protections. Under the FDCPA, collectors cannot call before 8 a.m. or after 9 p.m. in your time zone. They cannot call you at work if you tell them you are not allowed to receive calls there. They cannot threaten you with arrest, use obscene language, or repeatedly call to harass you. They also cannot lie about how much you owe or misrepresent their identity.
If a collector violates these rules, you have the right to sue them in federal court within one year of the violation. You may recover actual damages, statutory damages up to $1,000, and attorney fees. This is not just theoretical. Courts have awarded damages in thousands of cases, and simply mentioning that you know your rights can sometimes change a collector's tone.
Here are the key things a collector can and cannot do:
- Can: Call you between 8 a.m. and 9 p.m., send written notices, report the debt to credit bureaus, and file a lawsuit to collect.
- Cannot: Threaten violence, use profanity, call repeatedly to annoy you, lie about the debt, or contact your friends and family about the debt (except to locate you).
- Must: Send you a written validation notice within five days of first contact, stop contacting you if you send a written cease-and-desist letter, and verify the debt if you dispute it in writing within 30 days.
Understanding these boundaries gives you a framework for every call. You are not powerless. You are not at the mercy of someone who can say whatever they want. The law is on your side, and knowing it is the first step toward handling these calls with confidence.
What to Do During the First Collection Call
The first call is often the hardest because you are caught off guard. You may feel embarrassed, angry, or scared. That is normal. But how you respond in those first few minutes can set the tone for everything that follows. The goal is not to resolve the debt on the spot. The goal is to gather information, avoid saying anything that could hurt you later, and buy yourself time to think.
When a collector identifies themselves and says you owe a debt, do not confirm or deny anything yet. Do not say "Yes, that is my debt" or "I forgot about that." Do not make a partial payment or promise to pay. Do not give them your bank account information or debit card number. Instead, stay calm and ask questions. Write down everything they say, including the collector's name, the company name, the amount they claim you owe, and the original creditor.
Here is a simple script you can use:
- "I am not confirming or denying this debt right now. Please send me written validation of this debt."
- "What is the name of your company, and what is your address?"
- "What is the original creditor and the original account number?"
- "I will review your written notice and respond in writing. Please do not call me again until you have sent that."
After the call, send a written request for debt validation via certified mail with return receipt requested. Keep a copy of the letter and the receipt. Under the FDCPA, the collector must stop collection efforts until they provide validation. This gives you breathing room and forces them to prove the debt is real and that they have the right to collect it.
If the collector refuses to send validation or continues to call after you have requested it in writing, they are violating the law. Document every call, including the date, time, and what was said. This documentation becomes valuable evidence if you need to file a complaint or sue.
Verify the Debt Before You Pay Anything
Not every debt that a collector claims you owe is valid. Mistakes happen. Debt buyers sometimes purchase accounts with incomplete records and then try to collect from the wrong person or for the wrong amount. The statute of limitations may have expired, meaning they cannot legally sue you to collect. In some cases, the debt may have been discharged in bankruptcy or already paid.
When you receive the validation notice, review it carefully. It should include the amount of the debt, the name of the creditor, and a statement of your right to dispute the debt within 30 days. If anything looks wrong or incomplete, send a written dispute letter. The collector must then investigate and provide you with proof, such as a copy of the original signed agreement or a detailed payment history.
You should also check your credit reports from all three major bureaus (Equifax, Experian, and TransUnion) to see how the debt is being reported. If the collection account appears on your report, you can dispute it if it is inaccurate or if the collector cannot validate it. Under the Fair Credit Reporting Act, credit bureaus must investigate disputes and correct errors.
Here are the most common reasons a debt may not be valid or collectible:
- The statute of limitations has expired, meaning the collector cannot sue you.
- The debt was discharged in bankruptcy.
- The debt belongs to someone else with a similar name.
- The amount is incorrect, or the collector cannot prove you owe it.
- The debt was already paid or settled.
If the debt is valid and within the statute of limitations, you still have options. You can negotiate a settlement for less than the full balance, set up a payment plan, or seek help from a credit counselor. But you cannot make an informed decision until you know exactly what you are dealing with.
Know Your Rights Under the FDCPA
The Fair Debt Collection Practices Act is your strongest tool when dealing with collectors. It sets clear rules about what collectors can and cannot do, and it gives you the right to take legal action if they cross the line. Knowing these rights is not just about protecting yourself. It is about leveling the playing field.
One of the most powerful rights is the ability to demand that a collector stop contacting you. You can send a written cease-and-desist letter that tells them to stop all communication. Once they receive it, they can only contact you to confirm they are stopping or to notify you of a lawsuit. This does not make the debt go away, but it stops the calls and gives you peace of mind.
You also have the right to dispute the debt and demand validation. If you send a written dispute within 30 days of receiving the validation notice, the collector must stop collection efforts until they provide proof. If they cannot prove the debt is yours and that they have the right to collect it, they must stop trying.
Other important rights include:
- The right to sue a collector for violations and recover damages.
- The right to file a complaint with the Consumer Financial Protection Bureau (CFPB) or your state attorney general.
- The right to be free from harassment, threats, and false statements.
- The right to privacy, meaning collectors cannot discuss your debt with third parties.
If a collector violates your rights, you can file a complaint with the CFPB online or by phone. The CFPB collects complaints and often forwards them to the collector for a response. In many cases, this alone is enough to get a collector to back off. If the violation is severe, you may want to consult a consumer protection attorney who can advise you on whether to sue.
Negotiate a Settlement or Payment Plan
If the debt is valid and you want to resolve it, negotiation is often the best path. Collectors want to get paid, and they are usually willing to work with you if you approach them strategically. The key is to negotiate from a position of knowledge and leverage.
Before you make an offer, determine how much you can realistically afford to pay. Do not agree to a payment plan that will strain your budget or force you to miss other obligations. If you can pay a lump sum, you may be able to settle for less than the full balance. Many collectors will accept 40 to 60 percent of the total debt if you can pay it all at once. Some will go lower if the debt is old or if they have reason to believe you may file for bankruptcy.
When you negotiate, get everything in writing before you pay a dime. The agreement should state the amount you are paying, the fact that it satisfies the debt in full, and that the collector will not sell or report the remaining balance. If the collector agrees to remove negative information from your credit report, get that in writing too. Verbal promises are not enforceable.
If you cannot pay a lump sum, ask about a payment plan. Be clear about what you can afford each month, and do not let the collector pressure you into agreeing to more. If they refuse to work with you, you can escalate to a supervisor or send a cease-and-desist letter and wait for them to sue. In many cases, they will not sue if the amount is small or if they believe you are judgment-proof.
If you are dealing with multiple defaulted loans and collectors are calling from several companies, you may want to consider a debt management plan through a nonprofit credit counseling agency. These agencies can negotiate with creditors on your behalf and consolidate your payments into one monthly amount. This can simplify your finances and reduce the stress of constant calls.
When to Seek Professional Help
Sometimes, handling collection calls on your own is not enough. If the debt is large, if you are being sued, or if the collectors are particularly aggressive, it may be time to bring in a professional. A consumer protection attorney can review your case, tell you whether your rights have been violated, and represent you in court if necessary. Many attorneys offer free consultations and work on a contingency basis, meaning you do not pay unless they recover money for you.
Nonprofit credit counseling agencies can also help. They can review your entire financial situation, help you create a budget, and negotiate with creditors to lower interest rates or waive fees. They may also be able to set up a debt management plan that consolidates your payments. Be cautious of for-profit debt settlement companies that charge high fees and make promises they cannot keep. If a company asks for money upfront or guarantees they can eliminate your debt, walk away.
If you are considering bankruptcy, consult a bankruptcy attorney. Bankruptcy can discharge many types of unsecured debt, including defaulted loans, and it triggers an automatic stay that stops all collection calls immediately. It is a serious step with long-term consequences, but for some people, it is the best path to a fresh start.
If you need a loan to consolidate debt or cover an urgent expense while you work through your options, a connection service like LendersCashLoan can help you explore potential offers from multiple lenders with a single request. This can be useful if you need to borrow money to settle a debt or cover expenses while you negotiate. Just be sure to review all terms carefully and borrow only what you can afford to repay.
Protect Yourself Going Forward
Once you have resolved the defaulted loan or set up a plan, take steps to protect yourself from future collection calls. Check your credit reports regularly and dispute any errors. Keep copies of all correspondence with collectors, including letters, emails, and notes from phone calls. If you move, update your address with creditors and the credit bureaus so you do not miss important notices.
Consider setting up a dedicated email address or phone number for financial matters. This keeps collection calls separate from your personal life and makes it easier to track who is contacting you. If you receive a call from a collector, do not ignore it. Ignoring calls does not make the debt go away. It often makes things worse because the collector may escalate to a lawsuit.
Finally, remember that you are not defined by your debt. Millions of Americans have defaulted loans and faced collection calls. What matters is how you respond. By knowing your rights, verifying the debt, negotiating strategically, and seeking help when you need it, you can resolve the situation and move forward with your financial life.
Handling debt collection calls about a defaulted loan is stressful, but it is not impossible. With the right information and a clear plan, you can take control of the conversation, protect your rights, and work toward a resolution that fits your life. Take it one step at a time, and do not be afraid to ask for help along the way.