
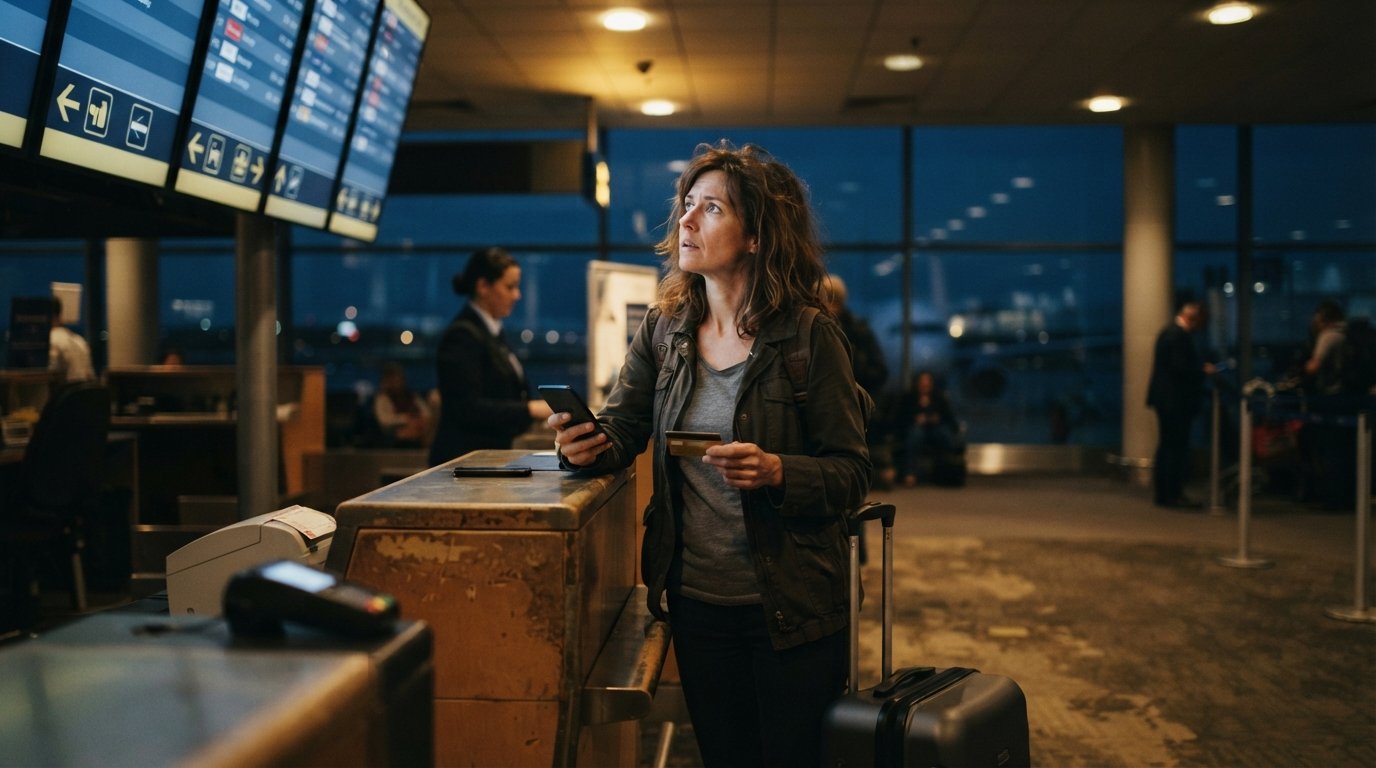
How to Cover Unexpected Travel Costs With a Fast Loan
Cover unexpected travel costs with a fast loan by matching the right structure to your trip and setting a repayment plan before you borrow.
By Irene Young
A phone call at midnight. A family emergency three states away. A transmission that quits two hundred miles from home. Unexpected travel costs rarely announce themselves in advance, and they seldom arrive at a convenient moment in your budget cycle. When you need to be somewhere fast and the money is not there, a fast loan can bridge the gap between the crisis and your next paycheck. The key is understanding which type of loan fits a one-time travel expense, how to qualify quickly, and how to repay it without turning a temporary shortfall into a long-term debt problem.
This guide walks through the situations that justify fast travel funding, the documents that speed up verification, how short-term and installment options compare for a single trip, and how to build a repayment plan before you borrow. It also explains how a loan connection service can put multiple offers in front of you in minutes so you can compare rather than settle.
Which Travel Emergencies Justify Fast Funding
Not every trip deserves a loan. Borrowing makes sense when the expense is genuinely unexpected and unavoidable, and when delaying travel would create a larger problem, such as missing a final goodbye or leaving a stranded family member without help. Bereavement travel is the clearest example: a death in the family often requires immediate airfare at prices that spike when tickets are booked last minute. Urgent family care is another, such as a parent or child hospitalized in another city who needs someone present for medical decisions or care coordination.
Stranded travel costs form a third category. A vehicle breakdown far from home can strand you with repair bills, rental cars, and unplanned hotel nights all at once. A canceled flight can leave you paying for a same-day rebooking or an overnight stay the airline will not cover. These situations share a common trait: the money is needed within days, not weeks, and the expense is a one-time event rather than an ongoing obligation.
Before you apply, ask three quick questions to confirm a loan is the right tool:
- Is the expense truly unexpected, or could it have been planned for?
- Will the trip resolve a specific problem that cannot wait?
- Can you identify a realistic repayment source, such as your next paycheck or a tax refund?
If you answer yes to all three, fast funding is reasonable. If the trip is discretionary or the repayment source is vague, a loan will likely add stress rather than relieve it. The goal is to solve the travel problem without creating a financial one that outlasts the trip.
How Fast Funding Works and What Speeds Up Verification
Fast loans for travel usually follow a simple path: you submit a short online request, a lender reviews your information, and if approved, funds are deposited into your bank account. Many online lenders advertise funding as soon as the next business day, though actual timing depends on the lender, your bank, and when you apply. Applying early in the day and on a business day improves your odds of same-day or next-day funding.
Verification is where most delays occur. Lenders need to confirm your identity, income, and bank account before releasing money. Having the right documents ready before you apply can shave hours or even a full day off the process. The items below are the ones most commonly requested for a fast personal or installment loan:
- Government-issued photo ID, such as a driver's license or passport
- Proof of income, such as recent pay stubs, bank statements, or benefit award letters
- An active checking account in your name for deposit and repayment
- Your Social Security number for identity and credit verification
Accuracy matters as much as preparation. A mistyped account number or an address that does not match your bank records can trigger a manual review that adds days. Fill out the request form carefully, use the same name and address that appear on your bank account, and respond quickly if a lender requests additional information. If you want to understand how repayment amounts translate into real costs before you commit, a loan repayment cost calculator can show you the total interest and fees attached to a given offer.
It also helps to understand who you are working with. A connection service such as StartCashLoan lets you complete one request form and be matched with third-party lenders in its network, which can be faster than applying to lenders one at a time. FreeQuotes.Loans works the same way: it is not a lender and does not make credit decisions, but it connects borrowers with lending partners who set their own terms. That distinction matters because your loan terms, interest rate, and repayment schedule come directly from the lender that funds you, not from the connection service.
Short-Term Versus Installment Loans for a One-Time Expense
Once you know fast funding is possible, the next decision is the loan structure. For a single travel expense, two broad categories fit: short-term loans, such as payday loans, and installment loans. They differ mainly in size, repayment timeline, and cost per month.
Short-term loans are typically small, often ranging from $100 to $1,000, and are usually due in a single payment on your next payday. They can be useful when the expense is modest and your next paycheck will comfortably cover repayment. The tradeoff is that a single lump-sum payment can strain your budget if the amount is large or if your paycheck is already committed to other bills. Rollover or extension fees can also make an already expensive loan more costly if you cannot repay on time.
Installment loans spread repayment across several fixed monthly payments over an agreed period. They often allow larger amounts, sometimes well beyond $1,000, and the smaller monthly payments can be easier to absorb alongside regular expenses. The total cost may be higher than a short-term loan if the term is long, but predictable payments reduce the risk of a missed due date. For a one-time travel expense such as airfare or a car repair, an installment loan is often the more manageable choice because it matches the cost to several paychecks instead of one.
Comparing the two comes down to three factors: the total amount you need, the size of the payment your budget can absorb, and how quickly you can repay without borrowing again. A modest expense you can clear in one paycheck points toward a short-term loan. A larger expense that would wipe out your next paycheck points toward an installment structure. Either way, request offers from more than one lender before deciding, since rates and terms vary widely for the same borrower profile.
Building a Repayment Plan Before You Borrow
The most common mistake borrowers make with emergency travel loans is treating repayment as a problem to solve later. That approach often leads to repeat borrowing, where a new loan pays off the old one and fees pile up with each cycle. The antidote is a repayment plan built before you accept any offer.
Start by identifying the exact source of repayment. For most borrowers that is the next paycheck, a bonus, a tax refund, or a reimbursement such as an insurance payout or employer travel credit. Write down the amount and the date it arrives, then compare it to the loan's due date. If the two do not align, choose a loan with a due date that falls after your income arrives, or select an installment structure with a first payment timed to your cash flow.
A simple framework helps keep the plan realistic:
- Total the trip costs, including fares, lodging, food, and any change fees, so you borrow once rather than in pieces.
- Match the loan amount to that total plus a small buffer, and no more.
- Set the due date or first installment after your confirmed income date.
- List the bills you will pay from the same paycheck and confirm the loan payment still fits.
- Identify one backup option, such as a payment extension policy or a family member who could help, in case income is delayed.
That backup step matters because late payments on any loan can damage your credit score and add fees. Knowing the lender's policy on extensions before you sign, rather than after you miss a payment, gives you a safer fallback. It also helps to keep the loan small: borrowing only what the trip requires reduces the repayment burden and lowers the chance you will need a second loan before the first is paid off.
Where to Find Fast Loan Offers and How to Choose
Speed and choice usually pull in opposite directions. Applying to a single lender is fast but limits your options; applying to many lenders individually is thorough but slow. A loan connection service resolves that tension by collecting your information once and circulating it to multiple lending partners. FreeQuotes.Loans is built for exactly this scenario: borrowers submit one request form, receive personalized offers from third-party lenders in the network, and compare terms before committing. The service charges no fee for the connection, and loan amounts range from $100 to $50,000 depending on the loan type and the borrower's qualifications.
When the offers arrive, compare them on four points rather than on the advertised monthly payment alone. The annual percentage rate tells you the true cost of borrowing. The total repayment amount shows what you will pay across the life of the loan. The due dates reveal whether payments align with your income. And the fees for late payments or extensions show what happens if plans change. A slightly higher rate with a due date that fits your paycheck can be cheaper in practice than a lower rate you cannot pay on time.
Borrowers with less-than-perfect credit should not assume they are excluded. Many lending partners in these networks work with applicants who have imperfect credit histories, provided they can show steady income, a valid ID, and an active bank account. Being upfront about your situation and having documentation ready improves your chances and speeds the process. The important thing is to borrow with a clear repayment plan, use the funds only for the travel emergency, and repay on schedule so the loan remains a one-time solution rather than a recurring cost.
Unexpected travel costs are stressful precisely because they arrive without warning. A fast loan cannot undo the emergency, but it can remove the financial barrier between you and the people or places that need you. Prepare your documents, compare more than one offer, choose a structure that matches your paycheck, and set the repayment plan before you sign. Do that, and a fast loan becomes a short bridge to your next paycheck instead of a long detour.