
How to Avoid Predatory Lending Practices: 2026 Guide
Spot red flags and verify lenders before you sign. Learn how to avoid predatory lending practices and protect your finances with smart comparison.
By Thomas Keller
Predatory lending can turn a short-term fix into a long-term financial trap. Whether you need cash for a medical bill, a car repair, or an overdue utility payment, the pressure to act fast makes borrowers vulnerable to lenders who profit from confusion and desperation. Learning how to avoid predatory lending practices is not about memorizing a list of red flags; it is about adopting a mindset of verification and skepticism before you sign anything. In this guide, you will learn to recognize the warning signs, verify lender legitimacy, and use comparison tools to protect yourself while still accessing the funds you need.
What Is Predatory Lending?
Predatory lending refers to any practice where a lender imposes unfair, deceptive, or abusive terms on a borrower. These terms often include excessively high interest rates, hidden fees, balloon payments, or loan structures designed to keep borrowers in a cycle of debt. Predatory lenders target vulnerable populations, including those with poor credit, limited financial literacy, or urgent cash needs. The harm is not just financial; it can lead to ruined credit, lost collateral, and severe stress.
Common predatory lending practices include:
- Charging APRs that far exceed market norms, sometimes exceeding 400% for short-term loans.
- Failing to disclose the full cost of the loan, including origination fees, late fees, and prepayment penalties.
- Encouraging borrowers to roll over or refinance loans repeatedly, trapping them in a cycle of fees.
- Using aggressive or illegal collection tactics, such as threats or harassment.
Understanding these tactics is your first line of defense. Predatory lenders rely on borrowers not reading the fine print or not knowing what is normal. By educating yourself, you can spot the difference between a legitimate short-term loan and a predatory trap.
Red Flags of Predatory Lenders
Recognizing red flags early can save you from months of financial hardship. Predatory lenders often use high-pressure sales tactics and promises that sound too good to be true. Here are the most common warning signs to watch for.
Guaranteed Approval
No legitimate lender can guarantee approval before reviewing your income, credit, and other qualifications. If a lender promises guaranteed approval regardless of your credit history, it is a major red flag. Such offers often come with hidden fees or extremely high interest rates that are only revealed after you provide personal information. Legitimate lenders assess risk and will only approve loans they believe you can repay.
Upfront Fees
Predatory lenders may ask for an upfront fee before disbursing the loan. This is often called an advance-fee loan scam. Legitimate lenders deduct fees from the loan proceeds or charge them at closing, but they do not require you to pay money before receiving funds. If you are asked to pay a fee via wire transfer, prepaid card, or cryptocurrency before getting your loan, walk away immediately.
No Written Terms
If a lender refuses to provide written loan terms or pressures you to sign without reading, that is a serious warning sign. Legitimate lenders are transparent about the loan amount, interest rate, fees, repayment schedule, and consequences of default. They provide a written agreement and encourage you to review it. Predatory lenders may rely on verbal promises that are not enforceable.
Other red flags include:
- High-pressure sales tactics, such as urging you to act immediately or claiming the offer expires soon.
- No physical address or contact information for the lender.
- Requests for sensitive information like your Social Security number before explaining the loan terms.
- Loans that require you to sign over the title to your car or home as collateral without clear disclosure.
Trust your instincts. If something feels off, it probably is. Taking a few extra minutes to verify a lender can prevent years of financial damage.
How to Verify a Lender's License and Reputation
Before doing business with any lender, verify that they are licensed to operate in your state. In the United States, lending laws vary by state, and legitimate lenders must comply with state licensing requirements. You can check a lender's license through your state's financial regulatory agency, often the Department of Financial Institutions or the Office of the Comptroller. Most states provide online databases where you can search for licensed lenders.
Beyond licensing, research the lender's reputation. Look for reviews on independent platforms, check with the Better Business Bureau, and search for complaints. Be cautious of lenders that have a pattern of negative reviews or unresolved complaints. However, keep in mind that online reviews can be manipulated, so look for detailed, consistent feedback rather than just star ratings. A legitimate lender will have a track record of transparent dealings and responsive customer service.
Another useful step is to check whether the lender is a member of a reputable industry association, such as the Online Lenders Alliance, which requires members to adhere to a code of conduct. While membership does not guarantee perfect behavior, it is a positive signal of accountability.
Read the Loan Agreement Carefully
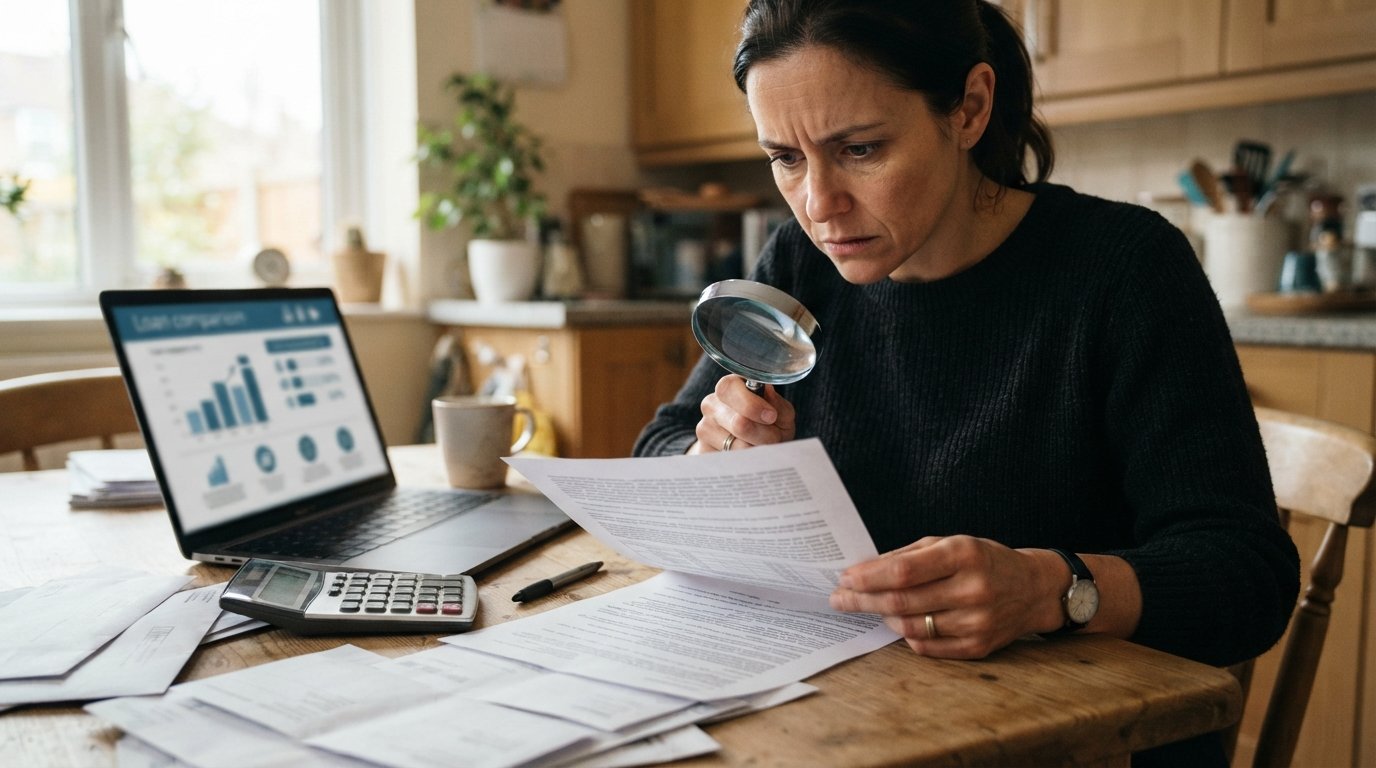
The loan agreement is the most important document you will sign. Predatory lenders count on borrowers skimming it. Before you sign, read every clause, especially those about interest rates, fees, repayment terms, and default consequences. Pay attention to the Annual Percentage Rate (APR), which includes both interest and fees, giving you the true cost of the loan. Compare the APR to typical rates for similar loans to see if it is reasonable.
Look for hidden fees, such as origination fees, late payment fees, prepayment penalties, and check processing fees. Understanding the total cost of the loan is crucial. For example, a payday loan with a $15 fee per $100 borrowed may seem small, but if rolled over, the effective APR can exceed 400%. Also, review the repayment schedule. Can you afford the payments? What happens if you miss a payment? Are there grace periods? Knowing these details prevents surprises.
If any part of the agreement is unclear, ask the lender to explain it in writing. Legitimate lenders will be happy to clarify. If a lender is evasive or rushes you, that is a red flag. You have the right to take the contract home and review it with a financial advisor or attorney if needed.
Use a Connection Service to Compare Offers Safely
One of the most effective ways to avoid predatory lending practices is to work with a connection service that matches you with multiple lenders. A service like ExpressCash connects consumers with a network of third-party lenders, allowing you to compare offers from multiple sources with a single request. This competition can help you find better terms and avoid the temptation of the first offer you receive, which may be predatory.
Using a connection service also provides a layer of verification. Reputable services vet their lending partners to ensure they are licensed and comply with applicable laws. However, you should still do your own due diligence on any lender you choose. The service does not make the loan; it simply connects you. Always read the terms from the lender before agreeing. FreeQuotes.Loans is another example of a connection service that helps borrowers compare loan options from a network of lenders, with no fees for the connection. By submitting one request, you can receive multiple quotes, making it easier to spot outliers with excessively high rates or fees.
When using a connection service, remember that loan terms are determined by the lender, not the service. The service can be a valuable tool, but it does not replace your responsibility to read and understand the loan agreement.
Know Your Rights and Where to Get Help
As a borrower, you have legal protections against predatory lending. Federal laws such as the Truth in Lending Act (TILA) require lenders to disclose key terms clearly. The Fair Debt Collection Practices Act (FDCPA) prohibits abusive collection tactics. State laws also impose caps on interest rates and fees for certain loan types. If you believe you have been a victim of predatory lending, you can file a complaint with your state's attorney general, the Consumer Financial Protection Bureau (CFPB), or the Federal Trade Commission (FTC).
Nonprofit credit counseling agencies can also help you understand your options and negotiate with lenders if you are already in a predatory loan. They can provide budgeting advice and debt management plans. Do not be ashamed to seek help; predatory lenders rely on isolation and fear.
Practical Steps to Protect Yourself
To summarize, here is a step-by-step approach to avoiding predatory lending practices:
- Educate yourself on typical loan terms and red flags.
- Verify the lender's license and reputation through state databases and independent reviews.
- Read the loan agreement thoroughly and ask questions about anything unclear.
- Compare offers from multiple lenders using a reputable connection service like FreeQuotes.Loans.
- Never pay upfront fees or provide sensitive information before understanding the terms.
- Know your rights and report suspicious practices to authorities.
By following these steps, you can access needed funds without falling into a predatory trap. Remember, urgency should not override caution. A legitimate lender will respect your need for clarity and time.
In conclusion, avoiding predatory lending requires vigilance, education, and a willingness to walk away from bad deals. Use comparison tools, read contracts, and verify lender credentials. Your financial well-being is worth the extra effort.