
Fixed vs Variable Personal Loan Rates: 2026 Guide
Fixed versus variable interest rates on personal loans explained: learn how each type affects your monthly payment and total cost, so you can choose with confidence.
When you compare personal loan offers, the interest rate you see is not just a number: it is the price you pay for borrowing money, and it can change how much you repay over time. Understanding the difference between fixed and variable interest rates on personal loans is one of the most important steps in choosing a loan that fits your budget. This guide explains how each rate type works, who controls the changes, and how to decide which one makes sense for your financial situation.
How Fixed and Variable Interest Rates Are Set
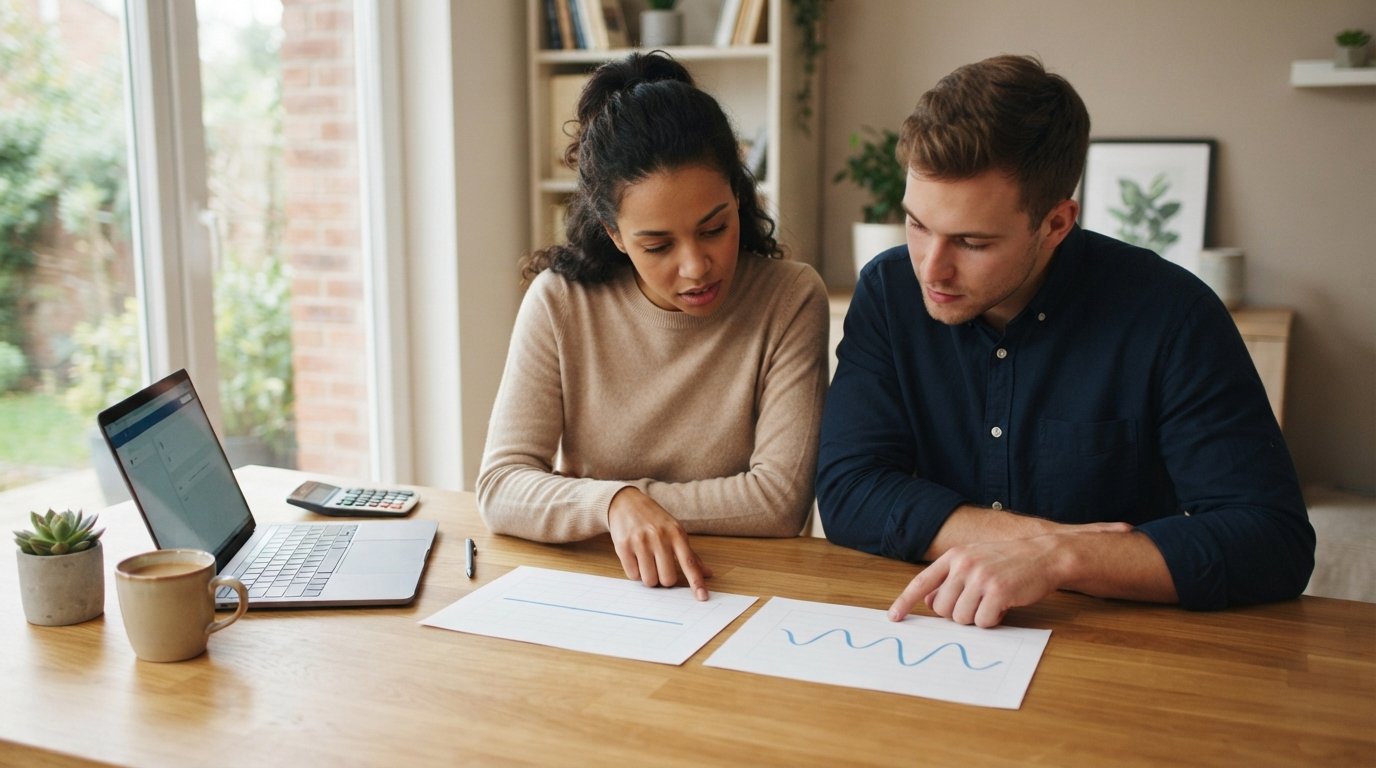
A fixed interest rate stays the same for the entire life of your loan. The lender locks in the rate when you sign the agreement, and it will not change even if market conditions shift. This means your monthly payment remains predictable, which can make budgeting easier. Fixed rates are common on personal loans, especially those from online lenders and credit unions, because they offer certainty for both the borrower and the lender.
A variable interest rate, on the other hand, can go up or down over time. It is typically tied to a benchmark index, such as the prime rate, plus a margin set by the lender. When the index changes, your rate adjusts, and so does your monthly payment or the length of your repayment term. Variable rates are more common on credit cards and home equity lines of credit, but some personal loans, particularly larger ones or those from traditional banks, may offer variable rates.
The key difference is who controls the changes: with a fixed rate, the lender sets the rate at the start and it does not move; with a variable rate, market forces and the lender's margin determine future adjustments. Before you choose, it is helpful to understand how lenders calculate the annual percentage rate (APR), which includes both the interest rate and any fees. For a deeper dive, see our guide on APR vs interest rate to compare offers accurately.
Why Short-Term and Subprime Loans Usually Carry Fixed Rates
If you are looking at payday loans, installment loans, or personal loans for bad credit, you will almost always see fixed rates. There are several reasons for this. First, short-term loans have brief repayment periods, often just a few weeks or months, so there is less time for rates to fluctuate. Lenders prefer the simplicity of a fixed rate for these products because it reduces administrative complexity and makes the loan easier to understand for borrowers who need fast cash.
Second, subprime borrowers (those with less-than-perfect credit) are often offered fixed rates because lenders want to limit their risk. A variable rate could increase payments unexpectedly, making it harder for borrowers to repay and increasing the chance of default. By locking in a fixed rate, lenders can better predict cash flow and borrowers can avoid payment shocks. Additionally, many online lenders that specialize in bad credit loans use fixed rates as a selling point: you know exactly what you will owe each month.
Third, regulations in some states require fixed rates for certain loan types, especially small-dollar loans. This protects consumers from unpredictable payment increases. So if you are seeking a short-term or subprime loan, you can generally expect a fixed rate, which simplifies comparison shopping.
Scenario Math: How Total Cost Differs Over the Loan Term
To see how fixed and variable rates affect what you repay, consider a simple example. Suppose you borrow $10,000 for a 5-year personal loan. With a fixed rate of 10%, your monthly payment is about $212.47, and the total interest paid over the life of the loan is approximately $2,748.20. Your payment never changes, so you can plan ahead with confidence.
Now imagine the same loan with a variable rate that starts at 8% but adjusts annually based on an index. In the first year, your payment might be lower, around $202.76. But if the index rises by 2% in the second year, your rate could increase to 10%, and your payment would go up accordingly. If rates continue to climb, your total interest could exceed the fixed-rate scenario. Conversely, if rates fall, you could pay less. The table below illustrates a possible path:
- Year 1: 8% rate, monthly payment $202.76, interest paid $764.52
- Year 2: 10% rate, monthly payment $212.47, interest paid $1,010.64
- Year 3: 12% rate, monthly payment $222.44, interest paid $1,258.32
- Year 4: 12% rate, monthly payment $222.44, interest paid $1,009.80
- Year 5: 12% rate, monthly payment $222.44, interest paid $749.88
In this scenario, the variable-rate borrower pays more total interest than the fixed-rate borrower if rates rise. However, if rates had fallen, the variable borrower could have saved money. The point is that variable rates introduce uncertainty: your total cost depends on future market movements, which no one can predict with certainty.
For short-term loans, the difference is even more pronounced because the repayment period is short. A payday loan with a fixed fee (which is essentially a fixed rate) might cost $15 per $100 borrowed, but a variable-rate short-term loan could see rates spike quickly. That is why most short-term products use fixed rates: to give borrowers a clear picture of the cost.
Questions to Ask Lenders About Rate Adjustments Before Signing
Before you commit to any loan, especially one with a variable rate, ask the lender specific questions to understand how your rate can change. These questions will help you avoid surprises and make an informed decision.
- Is the interest rate fixed or variable? If variable, what index is it tied to, and how often can it adjust?
- Is there a cap on how much the rate can increase at each adjustment or over the life of the loan?
- Will my monthly payment change if the rate adjusts, or will the loan term be extended instead?
- Are there any fees associated with rate adjustments, such as a cap fee or administrative charge?
- Can I convert a variable-rate loan to a fixed-rate loan later, and if so, what are the costs?
These questions are particularly important if you are considering a larger personal loan or a loan with a long repayment term. For short-term loans, the rate is usually fixed, but it is still wise to confirm. Remember that lenders are required to disclose the terms, so do not hesitate to ask for clarification. A reputable lender will welcome your questions and provide clear answers.
If you are using a connection service like StartCashLoan to find offers, you can ask the matched lenders these questions directly. StartCashLoan connects consumers with third-party lenders who may offer fixed or variable rates, and it is important to review each offer's terms carefully.
How to Match Rate Type to Your Repayment Certainty
Choosing between a fixed and variable rate depends on your financial situation, your risk tolerance, and how certain you are about your future income and expenses. Here are some guidelines to help you decide.
Choose a fixed rate if:
- You have a tight budget and need predictable monthly payments.
- You plan to repay the loan over several years and want to avoid payment shocks.
- You are borrowing for a necessary expense and cannot afford higher payments if rates rise.
- You have a low credit score and are offered a rate that is already high; locking it in prevents further increases.
Consider a variable rate if:
- You can comfortably afford higher payments if rates increase.
- You expect rates to fall in the near future.
- You plan to repay the loan quickly, so there is less time for rates to change.
- You are offered a significantly lower initial rate that makes the variable option attractive despite the risk.
For most borrowers seeking personal loans, especially those with less-than-perfect credit or urgent financial needs, a fixed rate is the safer choice. It provides peace of mind and makes it easier to plan your repayment. Variable rates can be beneficial in certain situations, but they come with uncertainty that may not be worth the potential savings.
When you compare offers through FreeQuotes.Loans, you can submit a single request and receive multiple quotes from lenders. This makes it easy to see which lenders offer fixed rates and which offer variable rates, and to compare the total cost of each option. The platform does not charge fees and is not a lender, so you can explore your options without obligation.
Final Thoughts on Fixed vs Variable Rates
Understanding fixed versus variable interest rates on personal loans explained above should give you a solid foundation for comparing offers. Fixed rates offer stability and predictability, while variable rates may offer lower initial costs but come with the risk of increases. For short-term and subprime loans, fixed rates are the norm, which simplifies decision-making. Always ask lenders about rate adjustments and consider your ability to handle potential payment changes. By matching the rate type to your repayment certainty, you can choose a loan that fits your budget and helps you achieve your financial goals.