
Emergency Loan for Car Repair with Bad Credit: 2026 Guide
Find an emergency loan for car repair with bad credit. Compare offers from multiple lenders and get back on the road fast with clear terms and no surprises.
By Thomas Keller
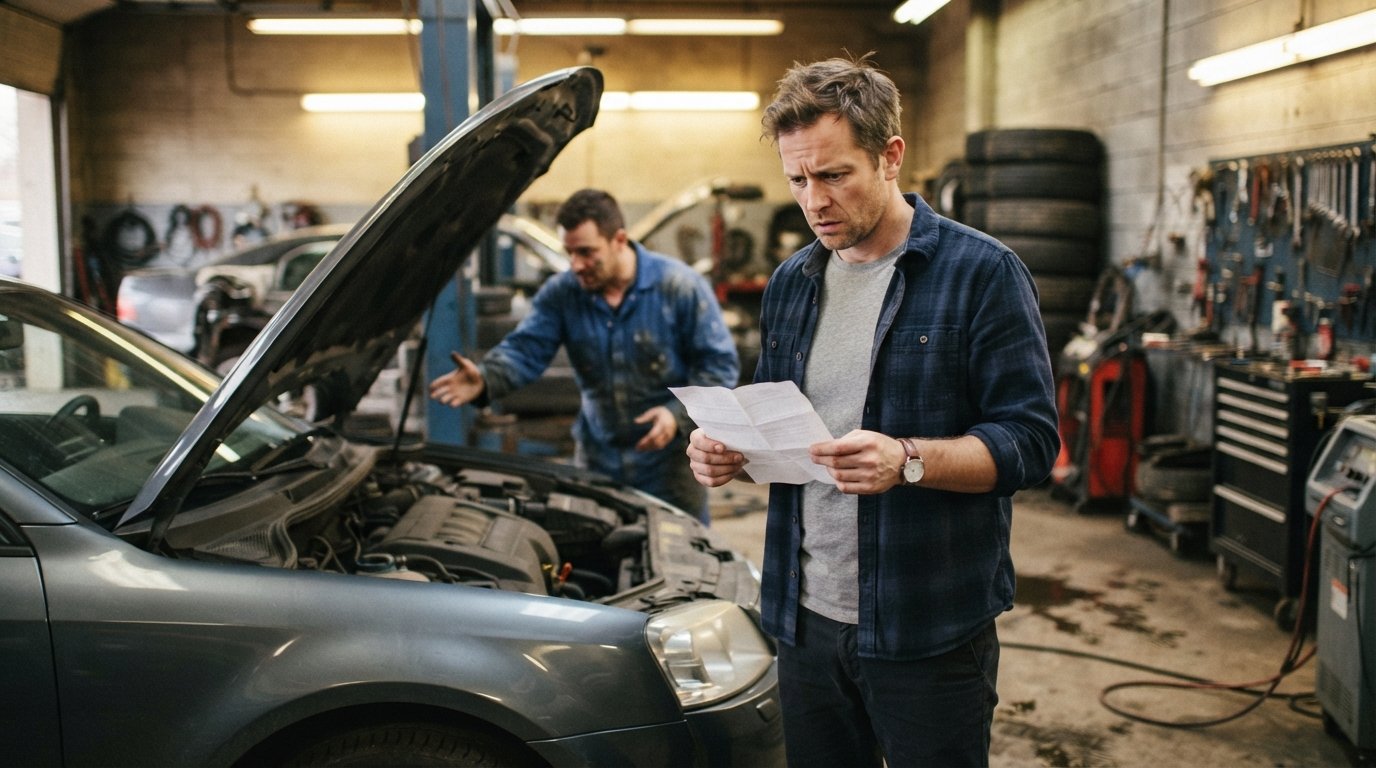
A grinding noise from your engine or a warning light flashing on your dashboard can turn a normal day into a financial emergency. When the repair estimate lands in your hands and your credit score is already bruised, the stress multiplies. You need your car to get to work, take your kids to school, and handle daily errands, but the cost of a major repair can easily run into hundreds or even thousands of dollars. The good news is that an emergency loan for car repair with bad credit is not a myth. There are legitimate options designed to help people in exactly your situation, and understanding how they work can save you time, money, and a lot of worry.
This guide walks you through the realistic paths available when you need cash fast for a car repair but your credit history is less than perfect. You will learn how personal loans, installment loans, and even payday loans can be used for auto repairs, how lenders evaluate applications from borrowers with bad credit, and how to compare offers so you do not get trapped in a cycle of debt. You will also find practical tips for negotiating with your mechanic and spotting predatory lenders before you sign anything. By the end, you should feel more confident about your next steps and know where to turn for help.
Why Car Repairs Create Financial Emergencies
Vehicles are essential for most Americans, yet they are also machines that break down without warning. A transmission failure, a blown head gasket, or a failed catalytic converter can cost anywhere from $500 to well over $3,000. For households living paycheck to paycheck, that kind of bill is impossible to absorb without borrowing. The problem is that many people with bad credit assume they cannot qualify for any type of loan, so they either ignore the repair or put it on a high-interest credit card. Neither choice is ideal.
The reality is that the lending market has changed. Many lenders now specialize in working with borrowers who have poor credit, previous repossessions, or even bankruptcies in their past. These lenders focus more on your current income and ability to repay than on your past credit mistakes. That does not mean approval is guaranteed, but it does mean you have options. The key is to understand which loan products fit your situation and to approach the process with clear eyes.
Types of Emergency Loans for Car Repairs
When you need money for a car repair and your credit is bad, you will typically encounter three main loan categories. Each has distinct features, costs, and repayment structures. Understanding the differences is the first step toward making a smart borrowing decision.
Personal Loans
Personal loans are unsecured installment loans that you can use for almost any purpose, including car repairs. You borrow a lump sum and repay it in fixed monthly installments over a set period, usually between 12 and 60 months. Interest rates vary widely based on your credit profile, but some online lenders work with borrowers who have fair or poor credit. Personal loans are often the best choice for car repairs because they offer predictable payments and do not require collateral. However, loan amounts for bad credit borrowers may be smaller, and interest rates can be higher than those offered to prime borrowers.
Installment Loans
Installment loans are similar to personal loans but often come from different types of lenders, including online installment lenders and some credit unions. They also allow you to repay over time in fixed installments. Installment loans for bad credit may have shorter terms and higher APRs than traditional personal loans, but they are still a structured way to finance a repair without relying on revolving credit. Some installment lenders report to credit bureaus, which means making on-time payments could actually help you rebuild your credit over time.
Payday Loans
Payday loans are short-term, high-interest loans typically due on your next payday. They are the most expensive option and should be approached with extreme caution. While they can provide fast cash for a car repair, they often come with fees and interest that can equal hundreds of dollars on a small loan. If you cannot repay the loan on time, you may be forced to roll it over, which can lead to a cycle of debt. Payday loans should only be considered as a last resort and only if you are absolutely certain you can repay the full amount on your next payday.
If you want a deeper look at how to cover a car repair with bad credit, including step-by-step guidance and additional options, you can read our detailed guide on how to cover a car repair with bad credit. It expands on the strategies mentioned here and helps you compare approaches.
How Bad Credit Affects Your Loan Options
Bad credit does not automatically disqualify you from getting a loan, but it does affect the terms you are offered. Lenders use credit scores to estimate risk. A lower score signals to lenders that you may be more likely to miss payments, so they compensate by charging higher interest rates or requiring larger down payments. In some cases, you may need to provide proof of steady income, a co-signer, or collateral to qualify.
That said, many lenders in the FreeQuotes.Loans network specialize in working with borrowers who have less-than-perfect credit. They may look at factors beyond your credit score, such as your employment history, income stability, and debt-to-income ratio. Some lenders even offer pre-qualification with a soft credit check, which lets you see potential offers without damaging your credit score. The important thing is to be honest about your credit situation and to shop around for lenders who explicitly state that they work with bad credit borrowers.
Comparing Loan Offers: A Critical Step
When you are desperate for cash, it is tempting to accept the first loan offer you receive. But comparing multiple offers is one of the most effective ways to protect yourself from high fees and predatory terms. Different lenders may offer vastly different APRs, repayment terms, and fee structures for the same loan amount. Taking an hour to compare can save you hundreds of dollars.
Here are the key factors to compare when evaluating loan offers:
- Annual Percentage Rate (APR): This includes both the interest rate and any fees, giving you a true picture of the loan's cost.
- Repayment terms: Longer terms mean lower monthly payments but more interest paid over time. Shorter terms mean higher payments but less total interest.
- Fees: Look for origination fees, prepayment penalties, late fees, and any other charges.
- Funding speed: If your car is in the shop, you may need funds quickly. Check how fast each lender can deposit money into your account.
- Customer reviews and lender reputation: Research the lender's track record and read reviews from other borrowers.
Using a loan comparison service like FreeQuotes.Loans can streamline this process. Instead of filling out multiple applications with different lenders, you submit one request and receive offers from multiple lending partners. This saves time and reduces the number of hard credit inquiries on your report. You can also use AdvanceCash to explore short-term loan options if you need a fast decision, but always compare offers from multiple sources before committing.
Avoiding Predatory Loans and High Fees
The market for bad credit loans includes many legitimate lenders, but it also attracts predators who prey on desperate borrowers. Predatory lenders often charge exorbitant interest rates, hide fees in the fine print, or use aggressive collection tactics. To protect yourself, watch for these red flags:
- Lenders who guarantee approval before reviewing your information.
- APRs that exceed 36% (a common threshold for predatory lending).
- Fees that are not clearly disclosed upfront.
- Pressure to sign immediately without time to review the terms.
- Lenders who ask for payment upfront before disbursing the loan.
Always read the loan agreement carefully, including the fine print. If something seems unclear, ask the lender to explain it. A reputable lender will welcome your questions and provide clear answers. Remember that an emergency loan for car repair with bad credit should help you get back on the road, not trap you in a cycle of debt.
Alternative Solutions to Consider
Before you commit to a loan, explore other ways to cover the repair cost. Sometimes a combination of strategies can reduce the amount you need to borrow. Here are a few alternatives:
- Negotiate with your mechanic: Ask if the shop offers payment plans or can prioritize the most critical repairs so you can spread out the cost.
- Use a credit card with a 0% introductory APR: If you have a credit card with available credit and a promotional rate, you might be able to finance the repair interest-free for a limited time.
- Borrow from friends or family: If possible, ask for a short-term loan from someone you trust. Just be sure to put the agreement in writing to avoid misunderstandings.
- Seek help from community organizations: Some charities and non-profits offer emergency assistance for car repairs to low-income individuals.
Even if you ultimately decide to take out a loan, exploring alternatives can reduce the amount you need to borrow or give you more time to shop for better loan terms.
Steps to Get an Emergency Loan for Car Repair with Bad Credit
If you have decided that a loan is the right solution, follow these steps to improve your chances of approval and get the best possible terms.
- Assess your repair cost and your budget: Get a written estimate from your mechanic and determine how much you can afford to repay each month.
- Check your credit report: Know your credit score and review your report for errors. Fixing mistakes can sometimes boost your score quickly.
- Gather required documents: Most lenders will ask for proof of identity, proof of income, and bank account information.
- Compare offers from multiple lenders: Use a comparison service or apply directly to lenders that work with bad credit.
- Review the terms carefully: Make sure you understand the APR, fees, and repayment schedule before signing.
- Receive funds and complete the repair: Once approved, funds may be deposited as soon as the next business day.
Following these steps helps you stay organized and reduces the risk of making a rushed decision. Remember that you are not alone in this situation, and many borrowers have successfully used emergency loans to cover car repairs and improve their financial standing over time.
Rebuilding Your Credit After the Loan
Taking out an emergency loan for car repair with bad credit is not the end of your financial story. In fact, it can be an opportunity to rebuild your credit. Many lenders report on-time payments to the major credit bureaus, so making every payment on time can gradually improve your score. Set up automatic payments or reminders to avoid missing due dates. Also, avoid taking on additional debt while you are repaying this loan, and work on building an emergency savings fund so you are better prepared for the next unexpected expense.
If you are ready to explore your options, FreeQuotes.Loans can connect you with lenders who may work with your credit situation. You can submit a single request and receive multiple offers, giving you the power to choose the loan that best fits your needs. With careful planning and a clear understanding of the terms, you can get your car back on the road and take control of your financial future.