
Emergency Dental Loan Options for Urgent Treatment Costs
Compare emergency dental loan options for urgent treatment costs. Get matched with multiple lenders through one request and find affordable repayment terms.
By Marcus Owens
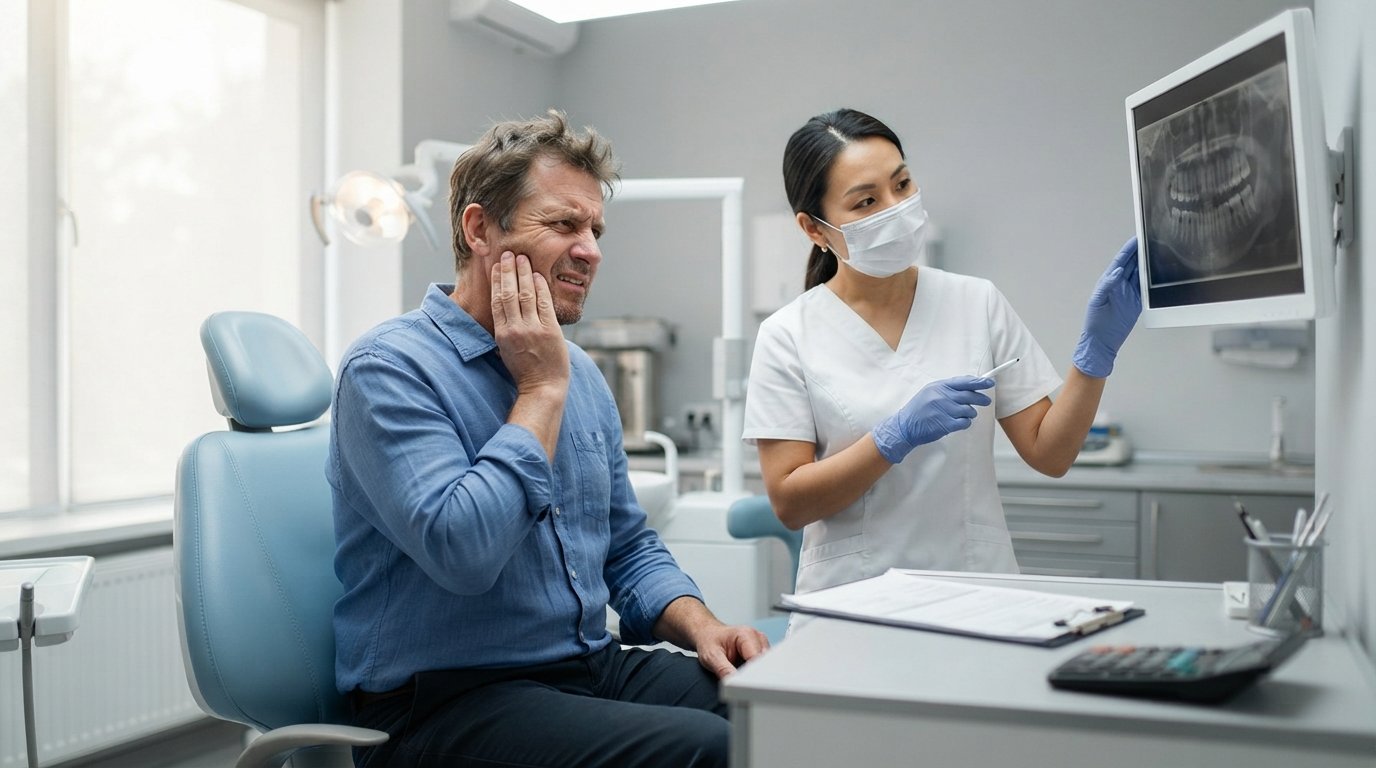
Your toothache does not care about your budget. When a sudden cavity, cracked tooth, or abscess demands immediate attention, the bill can arrive before you have time to plan. According to the American Dental Association, nearly half of adults without dental insurance delay care because of cost, and even those with coverage face out-of-pocket expenses that can run into the thousands. If you are facing an urgent procedure and your savings will not cover it, emergency dental loan options for urgent treatment costs can bridge the gap. This guide explains typical expenses, compares in-house payment plans with third-party loans, and shows you how to request multiple offers quickly so you can get treated without draining your emergency fund.
Typical Out-of-Pocket Dental Costs That Prompt Borrowing
Dental work is rarely cheap, and the most urgent procedures are often the most expensive. A simple filling might cost a few hundred dollars, but a root canal and crown can easily exceed $2,000. When an infection or trauma requires immediate care, you may not have the luxury of shopping around for the lowest price. Understanding the average costs helps you estimate how much you need to borrow and avoid surprise bills.
Here are common urgent dental treatments and their typical out-of-pocket ranges (before insurance, which may reimburse a portion later):
- Emergency exam and X-rays: $50 to $200
- Root canal (front tooth): $600 to $1,000
- Root canal (molar): $800 to $1,500
- Crown: $800 to $1,500
- Tooth extraction (simple): $150 to $300
- Tooth extraction (surgical): $300 to $650
- Dental implant (single tooth): $3,000 to $5,000
These figures vary by region and provider, but they illustrate why a single urgent visit can overwhelm a tight budget. If you have dental insurance, you may still be responsible for deductibles, coinsurance, and annual maximums, which often cap out at $1,000 to $2,000. That leaves a significant gap that many patients cover with a loan.
When you need cash fast, the last thing you want is a lengthy application process. FreeQuotes.Loans offers a free connection service that lets you submit one request and get matched with up to multiple lenders who may provide emergency dental loans for urgent treatment costs. The service is not a lender and does not make credit decisions, but it can save you time by presenting several options in one place.
In-House Dental Payment Plans vs. Third-Party Loans
Before you apply for a loan, ask your dentist whether they offer an in-house payment plan. Many practices provide interest-free financing for six to twenty-four months, especially for larger treatments. These plans are convenient because they keep everything under one roof, but they often require a credit check and may have limited availability. If your credit is less than perfect, you might not qualify for the best terms, or the practice may not offer in-house financing at all.
Third-party loans, on the other hand, come from independent lenders and can be used at any dental office. They typically fall into two categories: personal installment loans and short-term payday loans. Personal installment loans let you borrow a lump sum and repay it in fixed monthly payments over a set term, which makes budgeting easier. Payday loans are smaller, shorter-term advances that are due on your next payday; they can be useful for very small gaps but often carry high fees and annual percentage rates (APRs).
Here is a side-by-side comparison to help you decide:
- In-house payment plans: Often 0% interest if paid within the promotional period; approval depends on the dental practice's policies; may require a down payment.
- Personal installment loans: Fixed monthly payments; terms from 6 to 60 months; APRs vary widely based on credit; funds can be used for any dental expense.
- Payday loans: Small amounts ($100 to $1,000); very short terms (2 to 4 weeks); high APRs; best avoided if you cannot repay quickly.
For most patients facing a bill of $1,000 or more, a personal installment loan offers more predictable repayment than a payday loan. However, if you only need a few hundred dollars to cover an exam and antibiotics, a short-term option might suffice. Always compare the total cost of repayment, not just the monthly payment.
If you are exploring different borrowing structures, our guide on loan options explained breaks down how short-term funding works and can help you choose the right type of loan for your situation.
How to Submit One Request and Compare Multiple Offers Quickly
When you are in pain, you do not have hours to fill out applications on dozens of websites. The most efficient approach is to use a connection service that matches your request with multiple lenders. FreeQuotes.Loans is designed for exactly this scenario: you complete one simple form, and the platform shares your information with its network of third-party lenders who may extend an offer. There is no fee to use the service, and you are under no obligation to accept any offer.
Here is a step-by-step framework to get from application to funding as quickly as possible:
- Gather your documents: Have your government-issued ID, proof of income (pay stubs or benefit statements), and bank account details ready. Lenders will need these to verify your identity and ability to repay.
- Submit one request: Fill out the secure online form with the amount you need (for example, $2,000 for a root canal and crown) and your basic personal information. The process typically takes less than five minutes.
- Review your offers: You may receive multiple loan offers from different lenders. Compare the APR, monthly payment, term length, and any origination fees. Do not accept the first offer without checking the others.
- Choose and sign: Once you select an offer, review the loan agreement carefully. E-sign your documents and wait for the funds to be disbursed, which can happen as soon as the next business day.
Speed matters, but so does caution. A 2023 survey by the Federal Reserve found that 37 percent of adults would struggle to cover a $400 emergency expense, which is why many turn to loans. By comparing offers side by side, you can avoid the most expensive terms and find a repayment plan that fits your budget. For more tips on navigating the application process, see our article on StartCashLoan, which provides plain-language guidance on borrowing and budgeting.
Questions to Ask About APR and Term Before Accepting an Offer
The APR is the single most important number to understand because it reflects the true annual cost of borrowing, including interest and fees. A loan with a low monthly payment but a long term can cost you far more in total interest than a shorter loan with a slightly higher payment. Before you sign, ask the lender these questions:
- What is the APR? This includes both interest and fees, so you can compare offers apples to apples.
- What is the total repayment amount? Multiply your monthly payment by the number of payments to see the full cost.
- Are there any prepayment penalties? Some lenders charge a fee if you pay off the loan early; others do not.
- What happens if I miss a payment? Late fees and credit reporting can vary; understand the consequences before you borrow.
- Is the term flexible? Can you choose a shorter term to save on interest, or a longer term to lower monthly payments?
Also consider the source of the loan. Payday loans often carry APRs of 300 percent or more, while personal loans from reputable lenders may range from 6 percent to 36 percent depending on your credit. If you have bad credit, you may face higher rates, but comparing multiple offers can still help you find a more affordable option. Remember that FreeQuotes.Loans does not set the terms; all loan details are determined by the third-party lender you are matched with.
Finally, think about your repayment strategy. Will you be able to make the monthly payments comfortably? If your income is variable, a shorter term with higher payments might be risky. A longer term reduces monthly strain but increases total interest. Use a loan calculator to test different scenarios before committing. And if you have dental insurance, submit your claim as soon as possible; reimbursement can help you pay off the loan faster.
Protecting Your Credit and Avoiding Long-Term Debt
Taking out a loan for dental care can be a responsible move if you have a plan to repay it. However, missing payments can damage your credit score, making future borrowing more expensive. Set up automatic payments or reminders to ensure you never miss a due date. If you foresee difficulty, contact the lender before you fall behind; some offer hardship programs or modified payment plans.
Also, be wary of borrowing more than you need. It is tempting to round up for buffer, but every extra dollar accrues interest. Borrow only the amount required to cover the treatment. If your dentist offers a discount for paying in full upfront, compare that discount to the cost of the loan; sometimes it is cheaper to borrow a smaller amount and pay the discounted price.
Emergency dental loan options for urgent treatment costs are not a permanent solution to financial insecurity, but they can be a lifeline when you need care immediately. By understanding the costs, comparing in-house plans with third-party loans, and asking the right questions about APR and term, you can make an informed decision that protects your smile and your wallet. If you are ready to explore offers, start with a single request through FreeQuotes.Loans and see what options are available to you today.