
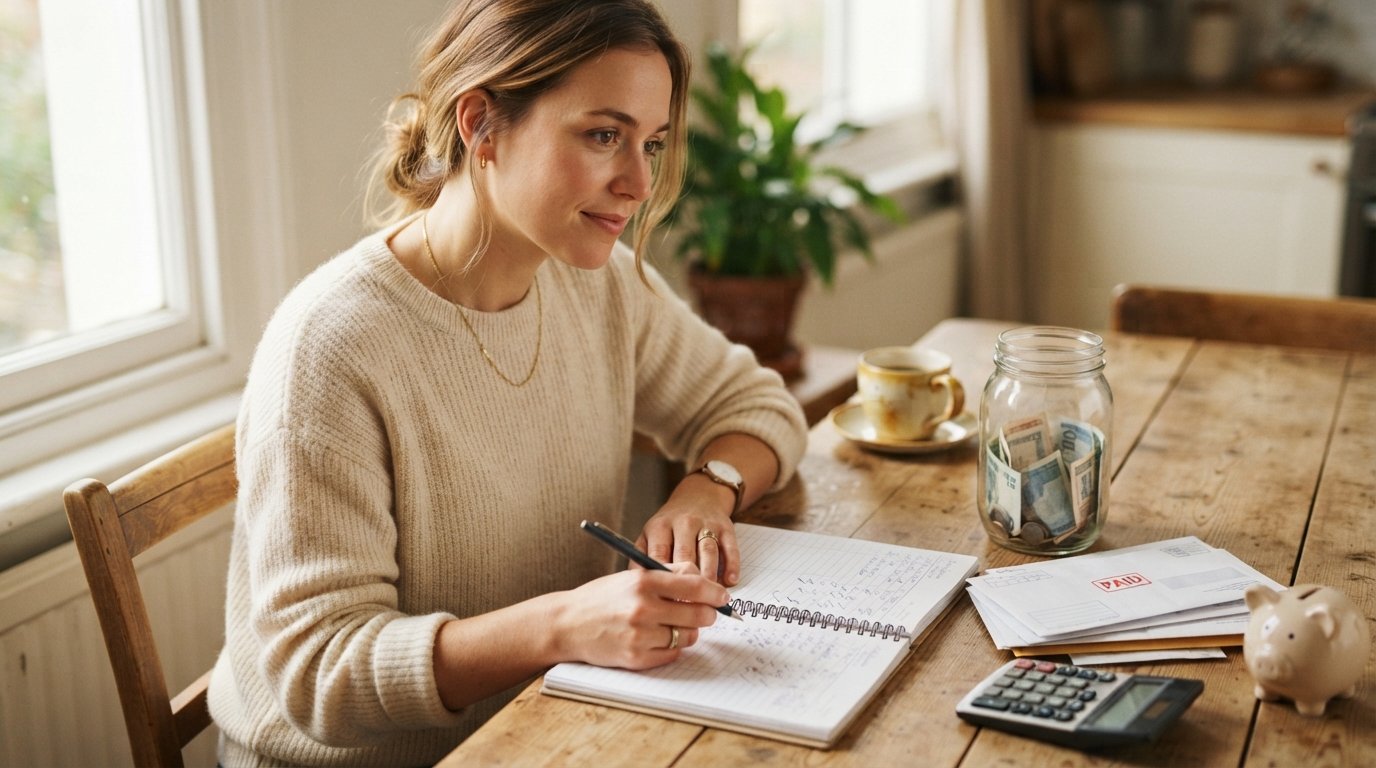
Building an Emergency Fund While Repaying a Loan
Building an emergency fund while repaying a loan is possible with small, automated transfers and smart windfall splits. Protect your repayment plan from surprises.
By Marcus Owens
You are staring at two financial goals that seem to pull in opposite directions: paying off a loan and setting aside cash for the unexpected. The good news is that you do not have to choose one or the other. With a realistic plan, you can make progress on both fronts without feeling like you are sabotaging either goal. In fact, building an emergency fund while repaying a loan can actually protect your repayment plan by preventing you from reaching for a credit card or a new loan when a surprise expense hits. This guide will walk you through a practical, step-by-step approach to growing your savings cushion even as you chip away at your debt.
Why You Need a Buffer Even When You Owe Money
It sounds counterintuitive: why save cash when you could use every spare dollar to pay down debt faster? The answer lies in risk management. Without an emergency fund, any unexpected expense, a car repair, a medical bill, or a sudden utility hike, can derail your loan repayment. You might be forced to miss a payment, incur late fees, or borrow again, often at a higher cost. That is why building an emergency fund while repaying a loan is not a distraction from your debt payoff; it is a crucial part of a stable financial plan.
Think of your emergency fund as a shock absorber. It keeps a small financial setback from becoming a full-blown crisis. When you have even a modest buffer, you can handle life's surprises without disrupting your loan schedule. This reduces stress and helps you stay consistent with your payments, which is good for your credit score and your peace of mind.
Set a Starter Goal Sized to Typical Small Emergencies
Traditional advice says to save three to six months of living expenses, but that can feel impossible when you are also repaying a loan. Instead, start with a mini emergency fund sized to cover common, smaller emergencies. For many people, $500 to $1,000 is enough to handle a minor car repair, a trip to urgent care, or a temporary gap in income. This starter goal is achievable and gives you a sense of accomplishment without months of sacrifice.
Once you hit that first milestone, you can reassess. You might decide to pause savings and focus on debt for a while, or you might continue to grow the fund slowly. The key is to start small and build momentum. Having a specific, modest target makes building an emergency fund while repaying a loan feel manageable rather than overwhelming.
To make your starter goal concrete, consider your most likely unexpected expenses. Do you drive an older car? A $500 car repair is a common surprise. Do you have a high-deductible health plan? A $300 urgent care visit could be a reality. Add up a few of these scenarios and aim to save that amount first. You can adjust the goal as your life changes.
Automate Small Transfers Around Loan Due Dates
One of the biggest challenges in building an emergency fund while repaying a loan is finding extra money to save. The solution is to automate small transfers that align with your cash flow. Set up a recurring transfer from your checking account to a dedicated savings account on a schedule that avoids overdrafts. For example, if your loan payment is due on the 15th, schedule your savings transfer for the 20th, after your paycheck has landed and the loan payment has cleared.
Even $10 or $20 per week adds up over time. The goal is consistency, not size. Automating the process removes the temptation to skip a transfer and helps you treat savings as a non-negotiable expense. Many banks allow you to set up multiple transfers, so you could save a small amount each week and a slightly larger amount after each payday. Just be sure to monitor your account balance to avoid overdraft fees, which would defeat the purpose.
Another strategy is to round up your purchases. Some banking apps will round your debit card transactions to the nearest dollar and transfer the difference to savings. This passive approach can quietly build your emergency fund while you focus on loan repayment. It is a low-effort way to make progress on both goals simultaneously.
Use Windfalls to Split Between Savings and Early Repayment
When you receive a windfall, such as a tax refund, a work bonus, or a cash gift, you have a powerful opportunity to accelerate both your emergency fund and your loan payoff. The key is to split the money strategically. First, top up your emergency fund to your starter goal if it is not already there. Then, direct the remaining amount toward your loan, ideally as an extra principal payment if your lender allows it without penalty.
For example, if you get a $1,200 tax refund and your emergency fund is at $300 with a $1,000 goal, you could put $700 into savings and $500 toward your loan. This split ensures you have a safety net while still making progress on debt. You can adjust the ratio based on your priorities and the size of the windfall. The important thing is to have a plan before the money arrives so you do not spend it impulsively.
If your loan has a prepayment penalty, which is rare but possible, check the terms before making extra payments. In most cases, lenders welcome early repayment. Splitting windfalls is a smart way to make building an emergency fund while repaying a loan a balanced effort rather than an all-or-nothing battle.
Avoid Re-Borrowing by Keeping a Buffer Before Taking on New Debt
One of the most common pitfalls when repaying a loan is the temptation to borrow again when a new expense arises. If you have no savings, you might turn to a payday loan, a credit card cash advance, or another high-cost borrowing option. This can create a cycle of debt that is hard to break. By maintaining a buffer, even a small one, you can cover minor emergencies without taking on new debt.
Before you consider any new loan, ask yourself if you have exhausted your emergency fund first. If the expense is larger than your buffer, explore other options such as a payment plan with the service provider or a short-term side gig to cover the cost. The goal is to avoid re-borrowing whenever possible. Each time you use your emergency fund instead of a new loan, you reinforce the habit of saving and reduce your overall debt burden.
When you do need to compare loan options for a major expense, consider using a service like StartCashLoan, which connects consumers with short-term and payday loan options through a network of third-party lenders. It is a free online connection service that can help you find financing if you truly need it, but it should be a last resort, not a first choice. Keeping a buffer helps you avoid that last resort.
Balance Your Loan Repayment Strategy with Savings
There is no one-size-fits-all formula for balancing debt repayment and savings. Some people prefer to pause savings entirely until their loan is paid off, while others feel more secure with a small cushion. The right approach depends on your risk tolerance, the size of your loan, and your job stability. If you have a stable income and a low-interest loan, you might lean more toward debt repayment while keeping a minimal buffer. If your income is variable or your loan has a high interest rate, a larger emergency fund might be a higher priority.
One useful framework is the debt avalanche versus debt snowball methods. With the avalanche, you pay extra toward your highest-interest debt first, which saves you the most money over time. With the snowball, you pay off the smallest debts first, which gives you quick wins and motivation. You can apply similar principles to your savings goal. For instance, you might focus on building a $500 buffer first (a quick win), then shift to aggressive debt repayment, then return to savings once the loan is smaller.
It is also worth reviewing your loan terms to see if there are opportunities to reduce your interest rate or monthly payment. Refinancing or consolidating your loan could free up cash flow that you can redirect to savings. If you are considering a new loan or refinancing, you can use a comparison tool to see offers from multiple lenders. Our article on how to select the right loan term for quick funding offers tips on choosing a loan that fits your budget and goals.
Track Your Progress and Adjust as Needed
Building an emergency fund while repaying a loan is a marathon, not a sprint. It helps to track your progress regularly, perhaps once a month, to see how far you have come. Celebrate small milestones, like saving your first $100 or making an extra loan payment. These wins keep you motivated and reinforce the habit.
As your financial situation changes, adjust your plan. If you get a raise, you might increase your savings transfers or your loan payments. If you face a temporary setback, you might pause savings for a month and then resume. The key is to stay flexible and not let a minor deviation derail your overall strategy. Remember that the goal is progress, not perfection.
Finally, keep your emergency fund in a separate, easily accessible account, like a high-yield savings account. You want it to be available when you need it, but not so accessible that you are tempted to dip into it for non-emergencies. A separate account also makes it easier to track your progress and avoid accidentally spending your buffer.
In the end, the combination of a small emergency fund and consistent loan payments creates a financial foundation that can withstand life's surprises. You do not have to choose between saving and repaying debt; with a thoughtful plan, you can do both. Start small, automate what you can, and use windfalls wisely. Your future self will thank you for the security and peace of mind that comes from having a buffer in place.